
Insurance Adjuster Tactics After a Multi Vehicle Crash
Insurers shift blame and make early low offers after multi vehicle crashes. Call (833)-248-4565 for a free case evaluation and protect your recovery.
By Desmond Vale
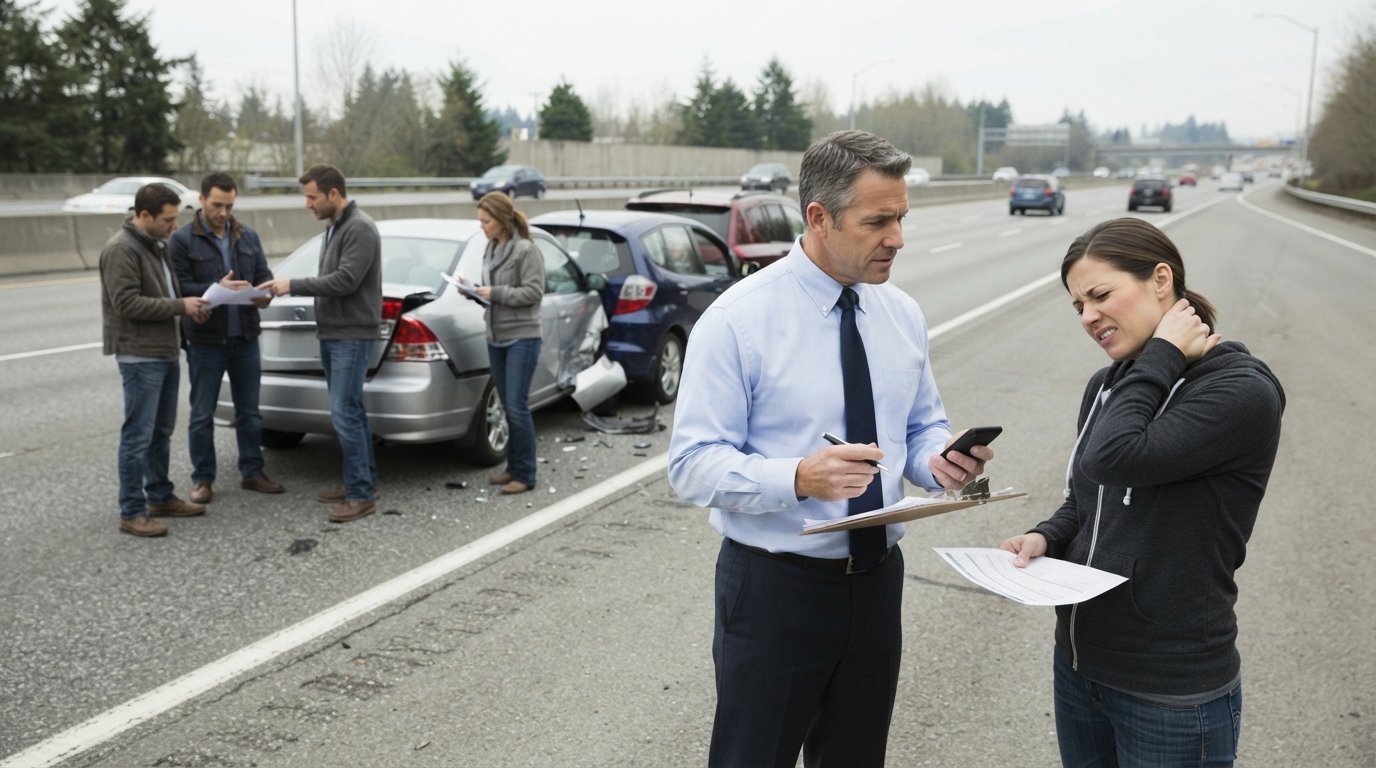
A chain-reaction collision on an interstate off-ramp leaves you with a crushed rear bumper, a sore neck, and three other drivers exchanging information in the breakdown lane. Within days, your phone rings. The voice on the other end is friendly, efficient, and already asking about your injuries. That caller is an insurance adjuster, and in a multi vehicle crash, the questions they ask and the order they ask them in are rarely accidental. Adjusters handling multi-party claims have one goal: to control how much their company pays, and to shift as much responsibility as possible onto the other drivers, or onto you. Understanding their playbook before your first recorded statement is one of the most practical ways to protect your recovery.
This guide breaks down the specific tactics adjusters use after a multi vehicle crash, from comparative fault calculations to early lowball offers, and shows what you can do at each stage. It is educational information, not legal advice, and it is designed to help you recognize pressure when you feel it.
How Adjusters Use Comparative Fault to Discount Multi-Party Claims
In a multi vehicle crash, the central question is not simply who caused the collision but what percentage of fault belongs to each driver. Most states use some form of comparative fault, and a handful use contributory negligence rules that can bar recovery entirely if you share any fault. Adjusters know these rules well, and they use them offensively. A common tactic is to assign you a percentage of fault early, before the full police report, witness statements, and medical records are available, then treat that number as settled fact in every subsequent negotiation.
Consider a typical four-car pileup. The rear driver may have been following too closely, but the adjuster for that driver will argue the middle driver braked suddenly without cause, and the adjuster for the middle driver will argue you stopped short. Each carrier has an incentive to inflate everyone else's fault, including yours, because every percentage point assigned to you reduces the payout its policyholder owes. Adjusters often float these allocations informally, in phone calls, long before any formal liability determination is made.
You can counter this by building your own fault timeline from day one. The following steps help you create a record that is hard for any single carrier to rewrite:
- Request the police crash report and confirm that all vehicles and drivers are listed, including any that left the scene.
- Collect contact information for every witness, not just the drivers, and note where each was positioned.
- Photograph vehicle damage from multiple angles, plus skid marks, debris fields, and road conditions.
- Keep a written timeline of what you observed and felt immediately after impact, including symptoms that appeared later.
That timeline matters because comparative fault arguments are won or lost on evidence created closest to the event. An adjuster who claims you contributed to the crash has a much harder time when you can produce witness statements and scene photos that contradict the story. If you are dealing with coordinated pressure from more than one carrier, our guide on how to deal with insurance adjuster tactics walks through additional countermeasures that apply across carriers.
Recorded Statements and Early Low Offers Before Treatment Ends
The recorded statement is the adjuster's most efficient tool in any crash, and it becomes far more dangerous in a multi vehicle case. In a single-car collision, the adjuster only needs to establish your fault or the other driver's fault. In a multi-party crash, the adjuster is listening for anything that can be used to assign fault to you or to another driver, and anything that can be used to minimize your injuries. Questions like "Did you see the other cars before the impact?" or "How fast were you going?" are not small talk. They are fault allocation questions dressed as conversation.
Adjusters also know that injured people often feel fine for the first 24 to 72 hours. Soft tissue injuries, concussions, and internal injuries frequently do not show symptoms until days after the crash. An early recorded statement locks in a version of events where you said you were not hurt, and that statement can be replayed in negotiations months later when your medical records tell a different story. For this reason, many experienced injury attorneys recommend giving no recorded statement to any adverse carrier until you have spoken with counsel and completed a medical evaluation.
Early low offers follow the same logic. Within a week or two, an adjuster may offer a few thousand dollars, framed as a fast, no-hassle resolution. The offer usually arrives before your treatment is complete and before the full extent of your injuries is known. Accepting it means signing a release that ends your claim against that carrier, and in a multi vehicle crash, it may also complicate your claims against the other drivers. The adjuster is not being generous; they are pricing in the risk that your claim is worth far more than the offer.
Treat every early offer as a data point, not a decision. Ask for the offer in writing, ask what it is based on, and decline to sign anything until your treatment has reached maximum medical improvement and you understand the liability picture across all vehicles.
Why Liability Disputes Between Carriers Can Stall Your Payout
In a multi vehicle crash, your claim may involve three, four, or more insurance companies, each with its own policyholder, its own policy limits, and its own theory of fault. Adjusters use this complexity deliberately. One carrier may say it is waiting on another carrier's liability decision before it can evaluate your claim. Another may argue that its driver bears no fault at all and refuse to make any offer. The result is a cycle of delays that can stretch for months while your medical bills accumulate.
This stalling tactic works because injured people often run out of patience or money before the carriers run out of reasons to wait. Adjusters know that a claimant facing collection calls is more likely to accept a discounted offer just to end the process. They also know that liability disputes between carriers are often resolved through inter-company arbitration or negotiation that you are not party to, and your claim can sit on a desk while that happens.
You can reduce the stalling advantage in several ways. First, send written demands for liability determinations and preserve proof of when you sent them. Second, gather the police report and witness statements yourself rather than waiting for a carrier to share them. Third, consider whether your own uninsured or underinsured motorist coverage, or medical payments coverage, can pay bills while liability is disputed. Finally, recognize that a formal demand package supported by medical records and a clear liability narrative forces carriers to respond on a timeline rather than on their own.
If the delays continue, an attorney can often break the logjam by communicating directly with all carriers, setting deadlines, and, where appropriate, filing suit. For readers comparing options for representation, platforms such as AttorneyLeads connect law firms with pre-screened legal leads, which is one way the legal industry matches injured claimants with attorneys who handle multi-party crash claims.
Documenting the Scene, Police Report, and Witness Contacts Early
Adjusters build their files from whatever evidence exists, and they know that evidence disappears quickly. Skid marks fade, debris is cleared, surveillance video is overwritten, and witnesses move or forget details. In a multi vehicle crash, the evidence you collect in the first days can determine whether the fault allocation lands in your favor or against you. The adjuster's advantage is that they handle these claims every day; your advantage is being on the scene and being motivated to document it thoroughly.
Start with the police report. In most jurisdictions, the responding officer's report includes a diagram of vehicle positions, statements from drivers and witnesses, and sometimes a preliminary fault determination. Request a copy as soon as it is available, review it for errors (wrong vehicle positions, missing drivers, incorrect injury notations), and ask the agency about the process for submitting corrections. Insurance adjusters rely heavily on police reports, so an accurate report is one of your strongest assets.
Witness contacts deserve equal attention. Collect names, phone numbers, and email addresses for every witness, and note where each was standing or driving when the crash occurred. A witness who saw the third car strike the second car before the second car hit you can dismantle an adjuster's theory that you stopped short. If possible, ask witnesses to write a brief statement while their memory is fresh, and keep those statements in a safe place.
Photographs and video complete the picture. Capture vehicle damage from multiple angles, the positions of all vehicles before they are moved, road and weather conditions, traffic signals, and any visible injuries. If nearby businesses or homes have security cameras, ask about preserving footage promptly, because many systems overwrite within days or weeks. Adjusters routinely discount claims that lack scene documentation, so treat these steps as part of your claim rather than an optional extra.
Tactics That Target Your Medical Treatment and Damages
Adjusters in multi vehicle cases also scrutinize your medical treatment, and some tactics are designed to create gaps or inconsistencies they can exploit. A common approach is to question whether your injuries were caused by this crash or by a prior condition, especially if you have a history of back or neck problems. Another is to argue that gaps in treatment show you were not seriously hurt. These arguments are particularly effective when the claimant delays treatment or stops and restarts care without explanation.
To counter them, seek medical attention promptly after the crash, follow your providers' recommendations, and document why any gaps occurred (for example, a referral delay or an insurance authorization issue). Keep a symptom journal that records pain levels, limitations, and how the injuries affect your work and daily life. Ask your providers to note in the records that your injuries are consistent with the crash mechanism. Adjusters respond to consistent, well-documented treatment, and they discount claims where the medical record is thin or contradictory.
Damage claims follow the same pattern. Adjusters may dispute lost wages without documentation, undervalue pain and suffering, or argue that a pre-existing condition explains your symptoms. Pay stubs, employer letters, tax returns, and a physician's work restrictions letter all help. If your vehicle was totaled, gather comparable vehicle listings to support the actual cash value. Each piece of documentation narrows the space an adjuster has to discount your claim.
When to Bring in Legal Help for a Multi Vehicle Crash Claim
Multi vehicle crashes are among the most complex claims an injured person can face, because fault, insurance coverage, and medical causation all interact. You may be able to handle a simple two-car fender bender on your own, but a chain-reaction crash with multiple carriers and disputed liability is a different matter. Signs that it is time to consult an attorney include: carriers blaming you for the crash, delays that stretch beyond a few weeks, an early offer that seems low relative to your injuries, and any dispute about whether your injuries came from this crash.
An attorney can gather evidence, communicate with all carriers, protect you from recorded statement traps, and evaluate whether your own coverage applies. Many personal injury attorneys work on contingency, meaning you pay nothing upfront and fees come from any recovery. FreeLegalCaseReview.com offers free, confidential case evaluations that connect injured people with qualified personal injury attorneys, and the service is not a law firm or a lawyer referral service. A complimentary case assessment can help you understand your options before you sign anything or give a statement.
Insurance adjuster tactics after a multi vehicle crash are designed to work quickly, before you have evidence and before you have advice. The countermeasure is to slow down, document everything, and avoid committing to a version of events or a settlement number before you understand the full picture. The adjuster's file will be built with or without your input; make sure the record includes your evidence, your medical treatment, and your account of what happened.