
What Happens If an Insurance Company Delays Claim Payment?
What happens if an insurance company delays claim payment? Learn your rights and how to pressure insurers. Call (833)-248-4565 for a free case review.
By Florian Beck
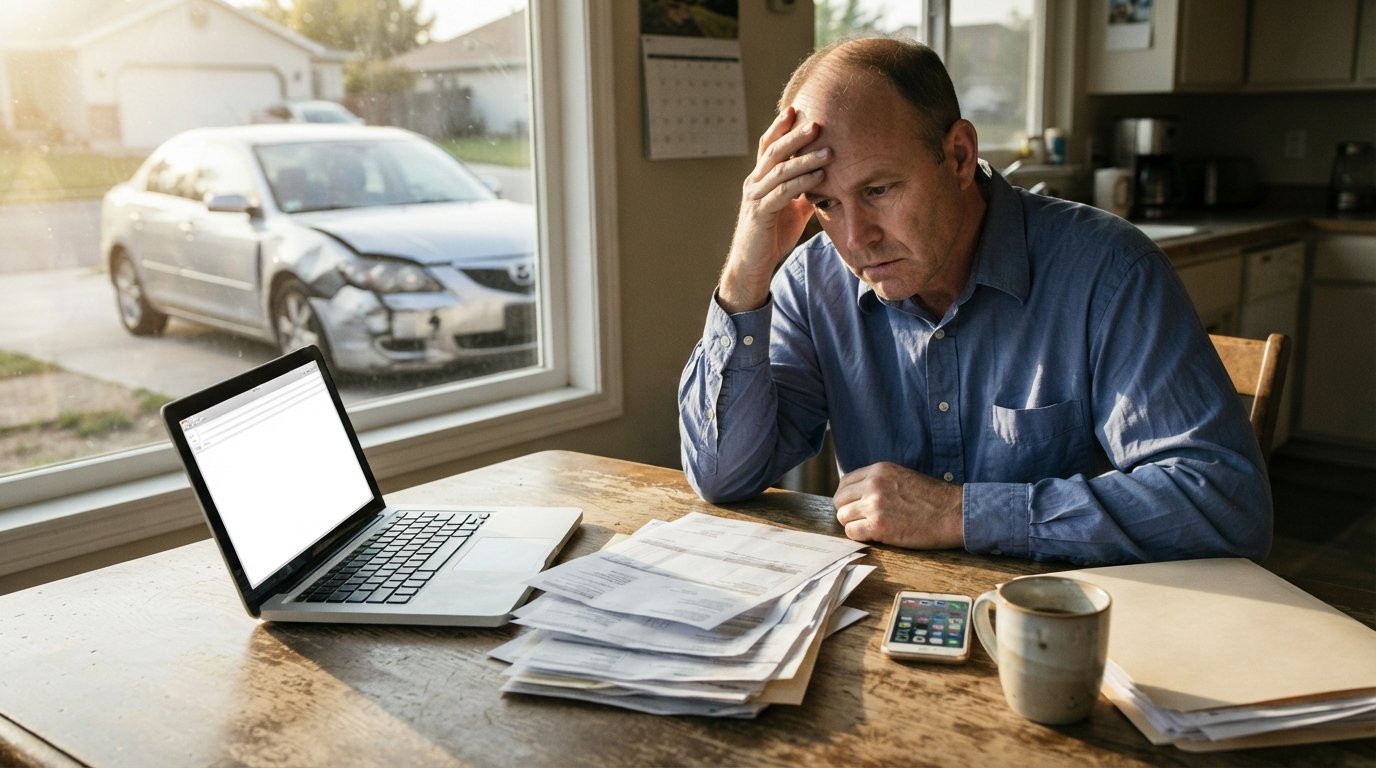
Your car is repaired, your medical bills are piling up, and the other driver's insurer has gone quiet. You have submitted every document they requested, answered every call, and still no check arrives. This scenario plays out for thousands of accident victims every year, and the frustration is compounded by a simple question: is this delay just normal bureaucracy, or is the insurer breaking the law? Understanding what happens if an insurance company delays claim payment is the first step toward protecting your rights and your financial recovery. Delays can be legitimate or they can be a calculated tactic designed to make you give up or accept less. This article explains the difference, outlines the legal deadlines insurers must follow, and shows you how to document a pattern of stalling that could support a bad faith claim. You will also learn when to escalate the matter to a state insurance department or an attorney, and how a free case evaluation can clarify your options without any upfront cost.
Legitimate Delays Versus Bad Faith Stalling Tactics
Insurance companies handle thousands of claims simultaneously, and not every delay is malicious. A legitimate delay often stems from genuine investigative needs. For example, the insurer may be waiting for a police report, medical records from multiple providers, or an independent medical examination. If you were in a multi-vehicle accident, the adjuster might need to sort out liability among several drivers, which takes time. In these situations, the delay is frustrating but not necessarily unlawful. The key is communication: a legitimate delay usually comes with a clear explanation and a timeline for resolution.
Bad faith stalling, by contrast, follows a different pattern. The insurer may repeatedly request the same documents, claim they never received paperwork you sent, or offer a lowball settlement that expires quickly. They might delay payment while knowing liability is clear, hoping you will become desperate and accept less. This is not just poor customer service; it can be a violation of state law. Bad faith claims arise when an insurer unreasonably denies, delays, or underpays a valid claim. The distinction matters because bad faith can expose the insurer to extra-contractual damages, including penalties and even emotional distress awards.
To tell the difference, watch for these red flags of bad faith delay:
- Repeated requests for information you have already provided multiple times.
- Failure to return phone calls or respond to emails within a reasonable time.
- Unexplained silence after you have submitted a complete demand package.
- Shifting explanations for the delay (first they need a report, then they need to "review with a supervisor").
- An offer that is far below the documented value of your injuries, presented as a final take-it-or-leave-it deal.
If you notice several of these signs, you may be dealing with a strategy rather than a backlog. Document everything, because a pattern of delay is the foundation of a bad faith claim.
State Prompt-Payment Laws and Statutory Deadlines
Every state has laws that require insurers to pay claims within a certain timeframe. These are known as prompt-payment laws, and they set specific deadlines for acknowledging a claim, investigating it, and either paying or denying it. The exact deadlines vary widely. For instance, some states require acknowledgment within 10 days, investigation completed within 30 days, and payment within 10 days after settlement. Others allow up to 60 days for investigation. California, for example, has a regulation that requires insurers to accept or deny a claim within 40 days after receiving proof of claim, with some exceptions. Virginia has similar rules, generally requiring prompt communication and payment within a reasonable time.
These laws also impose penalties on insurers that miss deadlines. In many states, the insurer must pay interest on the overdue amount, typically at a rate of 10% to 18% per year. Some states allow the insurance commissioner to fine the insurer for each violation. In cases of bad faith, the insurer may be liable for the full amount of the claim plus additional damages. Knowing your state's specific deadlines is crucial because it gives you a concrete timeline to reference when pushing back.
Here is a general framework for how prompt-payment laws work, though you should verify the exact numbers for your state:
- Acknowledgment: The insurer must confirm receipt of your claim, often within 10 to 15 days.
- Investigation: The insurer must complete its investigation within a set period, commonly 30 to 45 days after receiving all necessary information.
- Payment or denial: Once the investigation is complete, the insurer must either pay the claim or provide a written denial with specific reasons, usually within 10 to 15 days.
- Penalties for delay: If the insurer misses these deadlines without a reasonable excuse, it may owe interest, fines, or bad faith damages.
If your insurer has blown past these deadlines, you have grounds to file a complaint with your state's department of insurance. That complaint can trigger an investigation and sometimes speed up payment. But it is not the only remedy.
Documenting a Delay Pattern for a Bad Faith Claim
Building a bad faith case requires more than a single late payment. You need to show a pattern of unreasonable delay. That means keeping a detailed record of every interaction with the insurer. Start a claim journal and log the date, time, and substance of every phone call, email, and letter. Note the name of the adjuster you spoke with and what they promised. Save copies of all documents you send, and if you send them by mail, use certified mail with return receipt requested. If you send by email, keep the sent messages and any read receipts.
This documentation serves two purposes. First, it helps you prove that the insurer received your information and still failed to act. Second, it creates a timeline that an attorney can use to demonstrate bad faith. Without a clear record, the insurer may claim it never received your paperwork or that you were unresponsive. With a clear record, those excuses fall apart.
When you have gathered your evidence, you can take the following steps to escalate the delay:
- Send a formal demand letter: Write to the adjuster's supervisor, referencing your state's prompt-payment law and the specific deadlines missed. Demand payment within a set time, such as 10 business days.
- File a complaint with the state insurance department: This is a free service and often prompts the insurer to respond quickly. Include copies of your documentation.
- Consult an attorney: A personal injury lawyer can evaluate whether you have a bad faith claim and may take your case on a contingency fee basis, meaning you pay nothing unless you win.
Many people hesitate to involve a lawyer because they fear upfront costs. But most personal injury attorneys offer a free, no-obligation case review. If you are considering legal action, you can start by requesting a free case evaluation through a trusted platform like AutoInjuryAccident.com, which connects accident victims with participating attorneys nationwide. This can give you clarity on whether the delay you are experiencing rises to the level of bad faith.
For a deeper look at how to handle aggressive insurer tactics, including threats of litigation, see our guide on what to do when an insurance company threatens a lawsuit. It explains how to respond when the insurer shifts from stalling to intimidation.
When to Escalate: Attorney Involvement and State Insurance Departments
If your claim has been delayed for weeks beyond the statutory deadline, and you have documented your efforts to resolve it, it is time to escalate. Filing a complaint with your state's department of insurance is a good first step. The department will contact the insurer and require a response. This often lights a fire under the adjuster because no insurer wants a regulator asking questions. However, a department complaint may not result in immediate payment, and it does not compensate you for the delay itself.
Hiring an attorney is the next level of escalation. An attorney can send a demand letter that carries more weight than one from a consumer. If the insurer still refuses to pay, the attorney can file a bad faith lawsuit. In many states, you can recover not only the original claim amount but also penalties, attorney's fees, and sometimes damages for emotional distress. The threat of a bad faith lawsuit often motivates insurers to settle quickly and fairly. According to the Insurance Information Institute, bad faith claims have risen in recent years, and insurers are increasingly aware of the financial risk.
But you do not have to navigate this alone. FreeLegalCaseReview.com offers a free, confidential case evaluation to help you understand your rights. The platform uses a patented attorney selection process to connect you with top-rated legal professionals in your area. There is no obligation to retain, and the evaluation costs nothing. If you are tired of waiting and want to know whether you have a legal claim for delay, this is a low-risk way to find out.
Remember that time limits apply to bad faith claims as well. Every state has a statute of limitations for filing lawsuits, and it can be as short as one year from the date of the delay. If you wait too long, you may lose your right to compensation altogether. So if you suspect bad faith, act promptly.
In the end, what happens if an insurance company delays claim payment depends on the reason for the delay and your response. A legitimate delay may resolve with patience and communication. A bad faith delay requires documentation, escalation, and possibly legal action. By understanding your state's prompt-payment laws and keeping a detailed record, you can hold the insurer accountable. And if you need help, a free case evaluation can be the first step toward getting the compensation you deserve.