
What Is a Lowball Settlement Offer and How to Respond
Spot a lowball settlement offer and learn how to respond with evidence. Call (833)-248-4565 for a free case review and protect your recovery.
By Hector Winslow
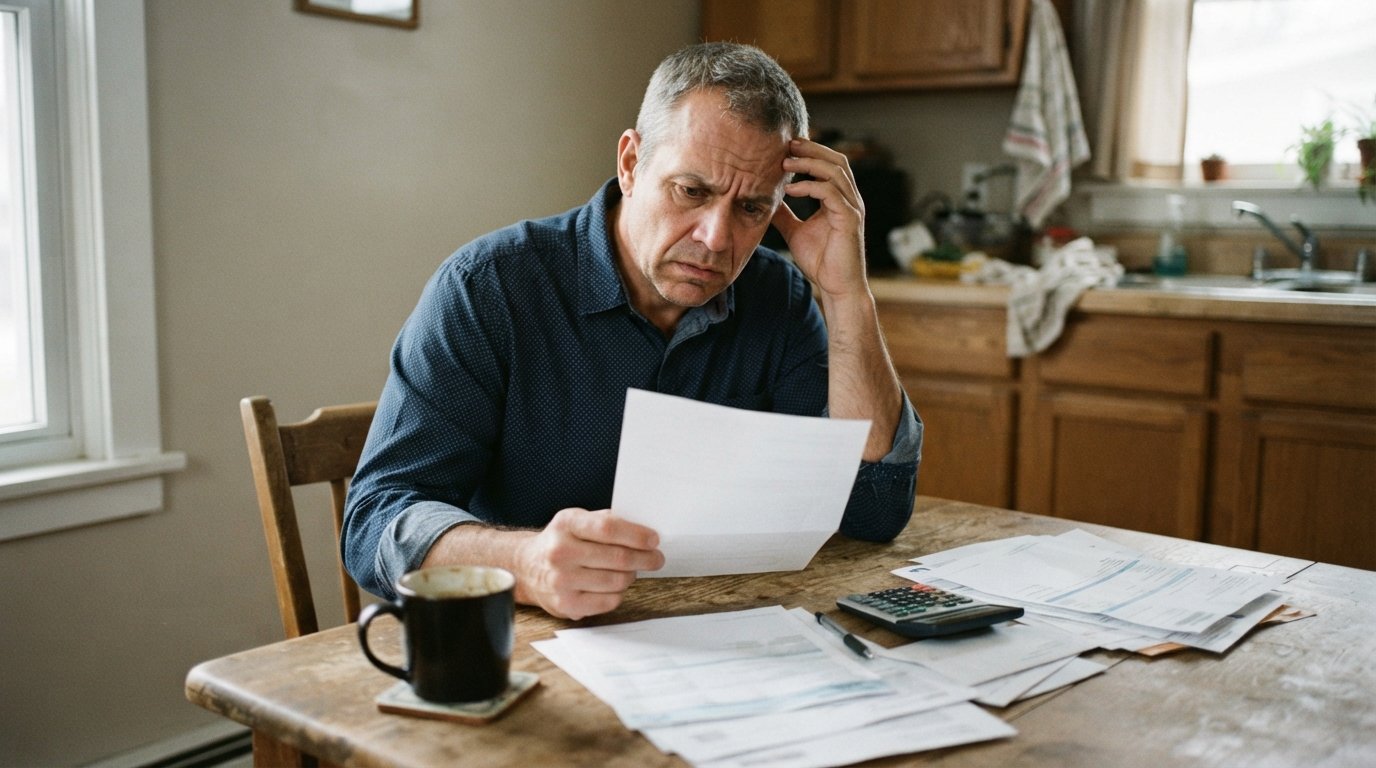
You open the letter from the insurance company, scan the number at the bottom, and feel your stomach drop. The figure is far less than what you expected, and it may not even cover your initial medical bills, let alone the weeks of lost work or the ongoing pain that still wakes you up at night. This is not an accident or a negotiating tactic you are imagining. It is a calculated strategy, and understanding what a lowball settlement offer is and how to respond is the first step toward protecting your financial recovery.
A lowball settlement offer is an initial proposal from an insurance adjuster that is intentionally set below the true value of your claim. It is designed to anchor negotiations in the insurer's favor, test whether you know your rights, and capitalize on the financial pressure you may be feeling after an accident. The adjuster is not your advocate. Their job is to close the file for as little as possible, as quickly as possible, and the first number they put on paper is rarely meant to be accepted at face value.
If you have already received an offer that feels wrong, you are not alone. Thousands of injury claimants face the same moment of uncertainty every year. The good news is that there are proven, documented ways to respond that shift the balance of power and force the insurer to take your damages seriously. This guide walks you through the warning signs of a lowball offer, the tactics adjusters use to justify it, and the exact steps you can take to counter with confidence.
Signs You Have Received a Lowball Settlement Offer
Not every disappointing offer is a lowball. Sometimes the initial number is simply a starting point in a good-faith negotiation. But certain patterns reveal that the adjuster is deliberately undervaluing your claim. Recognizing these signs early can save you from accepting a figure that will not cover your future needs.
One of the clearest indicators is an offer that ignores or minimizes future medical care. If your doctor has recommended surgery, physical therapy, or ongoing monitoring, the settlement should reflect those costs. An adjuster who calculates only the bills you have already incurred is either inexperienced or hoping you will not notice the gap. The same applies to lost earning capacity. If your injury prevents you from returning to your previous job or reduces your future income, that loss has a dollar value, and a fair offer must account for it.
Another red flag is a rapid offer made before you have finished treatment. Adjusters know that the full extent of an injury often takes weeks or months to become clear. A quick offer is often an attempt to lock you in before the true cost emerges. If the insurer pressures you to sign within days of the accident, that urgency is a signal, not a courtesy.
You should also be suspicious if the offer comes with a demand for a broad release of all claims, including ones you have not yet discovered. A legitimate settlement resolves known claims, but a lowball offer often tries to extract a release that covers future complications, unknown injuries, or even claims against other parties. That is not a standard term; it is a trap.
Finally, watch for an offer that is presented as final or non-negotiable. Insurance companies negotiate every day. An adjuster who claims there is no room to move is testing whether you will walk away or accept the first number. In most cases, there is room, but you have to ask for it with evidence.
How Insurance Adjusters Anchor Offers Low
The lowball offer is not random. It follows a playbook that adjusters learn early in their careers. The first move is to anchor the negotiation with a number well below the claim's actual value. Behavioral economics shows that people tend to gravitate toward the first figure they see, even when they know it is arbitrary. By setting a low anchor, the adjuster hopes to make a slightly higher counteroffer seem generous, even if it is still far from fair.
The second move is to control the information. Adjusters request medical records, wage statements, and repair estimates, but they rarely volunteer what they know about the full scope of your damages. They may calculate pain and suffering using a formula that suits the insurer, or they may simply omit that category from the initial offer. If you do not provide documentation for a loss, the adjuster will assume it does not exist.
A third tactic is to exploit financial pressure. If you are out of work, behind on bills, or facing collection calls, the adjuster may assume you will accept a quick, low payment rather than wait for a fair one. This is why lowball offers often arrive when you are most vulnerable. The insurer is counting on your need for cash to override your patience.
Understanding these tactics does not require you to become a negotiator overnight. It simply means you should never treat the first offer as a benchmark. The number is a starting point, and the information you provide next will determine whether it moves.
How to Respond to a Lowball Settlement Offer: A Step-by-Step Approach
Responding to a lowball offer is not about anger or confrontation. It is about documentation, patience, and a clear counterproposal. The following steps give you a structured way to push back while preserving your credibility and your claim.
- Do not accept or reject immediately. Thank the adjuster for the offer and ask for it in writing. A written offer gives you time to review the terms, and it creates a record of what was proposed. Avoid any verbal commitment, even a casual one.
- Gather your complete damages documentation. Collect all medical records, bills, imaging reports, prescription receipts, and doctor's notes. Obtain wage statements, tax returns, and a letter from your employer confirming lost time and reduced hours. If you have future treatment recommendations, get those in writing as well.
- Calculate a realistic case value. Add your economic damages (medical costs, lost wages, out-of-pocket expenses) and then consider non-economic damages such as pain, suffering, and loss of enjoyment of life. A common starting point is to multiply economic damages by a factor between 1.5 and 5, depending on the severity and permanence of the injury. This is not a precise science, but it gives you a defensible range.
- Write a counteroffer letter with evidence attached. State the amount you are requesting, explain the basis for it, and attach the documentation that supports each category of damages. Keep the tone professional and factual. Do not insult the adjuster or threaten litigation at this stage.
- Set a deadline and be prepared to walk away. Give the adjuster a reasonable time to respond, such as 10 to 14 business days. If the insurer refuses to move toward a fair figure, you retain the right to pursue other options, including filing a complaint with your state insurance department or consulting an attorney.
This process works because it replaces emotion with evidence. Adjusters respond to documentation. When you show that your medical bills are higher than they assumed, or that your lost wages are documented by an employer, the math changes. The anchor moves, and the negotiation becomes about facts rather than pressure.
For a deeper look at how to prevent these situations before they start, our guide on how to avoid low insurance settlement offers explains the early steps that protect your claim from the first day.
What Information Changes the Math in Your Favor
Insurance adjusters are not persuaded by frustration. They are persuaded by records. The more complete your documentation, the harder it becomes for the insurer to justify a low number. Three categories of information tend to have the greatest impact.
First, medical records that establish the full scope of your injury. This includes not just emergency room visits but also specialist consultations, imaging, and treatment plans. If your doctor has noted that your condition is permanent or that you will need future care, that note is valuable. Obtain a letter from your treating physician that explains your prognosis, your restrictions, and the expected cost of future treatment.
Second, wage loss documentation. Pay stubs alone are not enough. You need a statement from your employer that confirms your position, your rate of pay, the hours you missed, and any reduction in your ability to work. If you are self-employed, tax returns and client invoices can serve the same purpose. The goal is to show the insurer that your lost income is real and calculable.
Third, evidence of non-economic damages. Pain and suffering is harder to document, but it is not impossible. Keep a daily journal that records your pain levels, your limitations, and the activities you have had to give up. Statements from family members or friends can corroborate how your life has changed. Photographs of visible injuries and any modifications you have made to your home or vehicle can also help.
When you present this information in an organized way, you are not just asking for more money. You are showing the adjuster that a jury could see the same evidence. Insurers settle cases based on risk, and a well-documented claim is a risk they would rather resolve than litigate.
When a Personal Injury Attorney Adds Leverage
There is a point in many negotiations where self-representation reaches its limit. If the adjuster continues to lowball you despite clear documentation, or if your injuries are severe enough to require long-term care, an attorney can change the dynamics of the negotiation. Attorneys bring resources that individual claimants often lack: access to medical experts, the ability to file a lawsuit, and the credibility that comes from a professional who negotiates with insurers every day.
One of the most significant advantages is the attorney's ability to see the case from a litigation perspective. An adjuster who knows you are represented by counsel must consider the cost of defending a lawsuit, the risk of a higher verdict, and the potential for bad-faith claims. That changes the math. Studies and industry data consistently show that represented claimants recover more on average than unrepresented ones, even after attorney fees are deducted.
If you are unsure whether your case warrants legal help, a free case evaluation can provide clarity. Platforms such as FreeLegalCaseReview.com connect injury victims with qualified personal injury attorneys through a free, confidential process. There is no obligation to retain anyone, and the evaluation can help you understand whether your offer is fair or whether you have room to push for more. For consumers who want to understand their rights when dealing with legal professionals or fee disputes, resources like AttorneyLawsuit offer additional context on attorney-related legal issues.
Risks of Accepting a Quick Settlement
The pressure to settle quickly is real. Bills pile up, the accident disrupted your routine, and the insurer's offer may feel like a lifeline. But accepting a quick settlement carries risks that can haunt you for years.
The most serious risk is the release of claims. When you sign a settlement agreement, you are typically giving up your right to pursue any further compensation for the injuries covered by that release. If you later discover that you need surgery, or that your injury is more serious than initially thought, you cannot go back to the insurer for more money. The release is final.
Another risk is underestimating future costs. A settlement that covers today's bills may not cover the treatment you need next year or the income you will lose if you cannot return to work. Once you accept, the insurer is off the hook. That is why it is critical to wait until your treatment is complete or your doctor has provided a clear prognosis before you agree to a final number.
Finally, a quick settlement may shortchange non-economic damages. Pain and suffering, emotional distress, and loss of enjoyment of life are real losses, and they have value. An adjuster who rushes to close the file is often hoping you will not ask for them. If you accept without raising those categories, you may leave significant compensation on the table.
Practical Tips for Negotiating with Confidence
Negotiation is a skill, but it is one you can learn. Start by knowing your bottom line. Before you speak to the adjuster, decide what number you would accept and what number you would need to feel whole. Write it down. Having a clear target keeps you from being swayed by the adjuster's framing.
Keep every communication in writing. Email and letters create a record, and they give you time to think before you respond. If the adjuster calls, take notes and follow up with a summary email. This practice protects you if the insurer later disputes what was said.
Do not be afraid to ask questions. If the adjuster says a particular expense is not covered, ask why. If they cite a policy limit, ask for the policy language. If they claim your injury is not serious, ask what medical evidence they reviewed. The answers often reveal gaps in their analysis that you can address with additional documentation.
Finally, remember that you are not required to accept any offer. The insurer wants to close the claim, but you have the right to wait, gather more evidence, and seek legal advice. Patience is a negotiating tool, and it is often the most effective one.
If you have received a lowball offer and want to understand your options, a free case evaluation can help you see the full picture. FreeLegalCaseReview.com offers confidential, no-obligation assessments that connect you with qualified attorneys who can review your claim and advise you on next steps. The service is free, and there is no pressure to retain anyone. Understanding what is a lowball settlement offer and how to respond is the first step toward a fair resolution, and you do not have to navigate it alone.