
Uninsured and Underinsured Motorist Claims After a Crash
Uninsured and underinsured motorist claims after a crash can cover the gap when the at-fault driver cannot pay. See how to protect your recovery.
By Owen Harrison
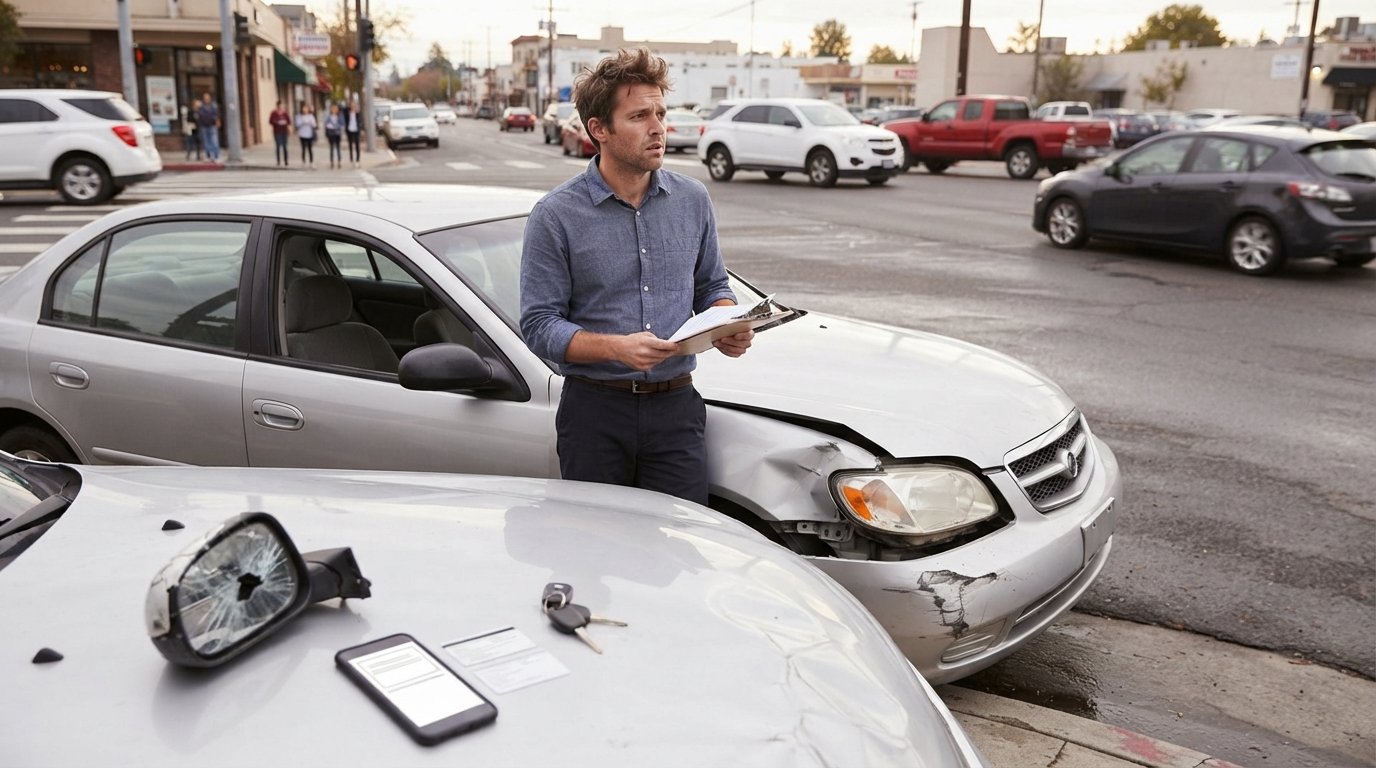
You did everything right. You stopped at the red light, kept your distance on the highway, and drove defensively through the intersection. Then a driver who either has no insurance or carries only the state minimum slams into your vehicle, and you are left with mounting medical bills, a damaged car, and lost wages. The at-fault driver's policy, if it exists at all, will not come close to covering your losses. This is the exact scenario that uninsured and underinsured motorist claims after a crash are designed to address, and understanding how these claims work can mean the difference between financial recovery and financial ruin.
Many crash victims assume that because the other driver caused the accident, the other driver's insurance will simply pay. That assumption collapses quickly when the at-fault motorist has no coverage or carries limits far below the actual cost of your injuries. Your own auto policy may hold the key to recovery through uninsured motorist (UM) and underinsured motorist (UIM) coverage, but insurers do not hand over that money without a fight. This article walks through what these coverages are, how claims unfold, what evidence matters, and how to protect your right to compensation.
What Uninsured and Underinsured Motorist Coverage Actually Does
Uninsured motorist coverage, commonly called UM, steps in when the driver who caused your crash has no liability insurance at all. That includes drivers who let their policies lapse, drivers who flee the scene in a hit-and-run, and in some states, drivers whose insurer denies coverage after the fact. Underinsured motorist coverage, or UIM, applies when the at-fault driver does have insurance, but the policy limits are too low to cover the full extent of your injuries and damages. For example, if the other driver carries a $25,000 bodily injury limit and your medical bills and lost income total $90,000, your UIM coverage can make up the difference, up to your own policy limits.
These coverages are not identical from state to state. Some states require insurers to offer UM and UIM coverage, while others make it optional. Some states treat UM and UIM as a single combined coverage, and others separate them. The limits you purchased, the language of your policy, and the laws of your state all shape what you can recover. This is why reading your declarations page carefully after a crash is one of the first practical steps you can take. The declarations page lists your coverage types and limits in plain numbers, and it tells you whether you even have a UM or UIM claim to pursue.
It also helps to understand that UM and UIM claims are first-party claims. You are not suing the other driver directly. You are making a claim against your own insurance company, with which you have a contract. That distinction matters because your insurer owes you duties under that contract, but it is still a business that wants to minimize payouts. Even though you are their policyholder, the adjuster handling your UM or UIM claim is not automatically on your side.
How Uninsured and Underinsured Motorist Claims After a Crash Unfold
The claims process for UM and UIM coverage follows a general sequence, though the details vary by state and by insurer. Understanding that sequence helps you avoid missing deadlines or damaging your claim through an early misstep. The most important early move is notifying your own insurer promptly. Most policies require reasonable notice, and delays can give the insurer grounds to dispute coverage.
After notice, the insurer will typically investigate the crash, request a recorded statement, and ask for medical records and bills. This is where crash victims often make costly mistakes, such as giving a broad recorded statement before they know the full extent of their injuries or signing a release too early. The investigation stage is also when the insurer may dispute fault, argue that your injuries pre-existed the crash, or claim that the at-fault driver actually had adequate coverage.
Here is a simplified framework for how these claims typically progress:
- Notify your insurer and confirm your UM/UIM limits. Report the crash, request a copy of your declarations page, and open a claim under the correct coverage.
- Document the at-fault driver's insurance status. Obtain the police report, the other driver's insurance information, and any denial letter from that insurer.
- Build your damages record. Collect medical records, billing statements, wage loss documentation, and evidence of pain, suffering, and lifestyle impact.
- Submit a demand package to your UM/UIM carrier. Present liability, damages, and the gap between the at-fault driver's limits and your total losses.
- Negotiate or proceed to arbitration or litigation. If the insurer disputes the claim or undervalues it, formal dispute resolution may be necessary.
Each of these steps has its own traps. For example, some policies require you to exhaust the at-fault driver's liability limits before UIM coverage applies, which means you may need to settle with the other insurer first. Other policies allow you to seek UIM benefits without waiting, depending on state law. Knowing which rule applies in your case prevents you from accidentally forfeiting coverage.
The Evidence That Makes or Breaks a UM or UIM Claim
Because UM and UIM claims are made against your own insurer, the evidence you assemble serves two purposes: it proves the at-fault driver's inadequate coverage, and it proves the full value of your damages. The first part is often straightforward. A police report, an insurance card with low limits, or a denial letter from the other driver's carrier establishes the coverage gap. The second part is where claims are won or lost.
Your damages record should be thorough and consistent. Medical records should document the mechanism of injury, the diagnosis, the treatment plan, and the prognosis. Gaps in treatment are one of the most common arguments insurers use to reduce or deny claims, so continuity of care matters. Wage loss documentation should come from your employer and should specify the dates and amount of income you lost. If your injuries affect your ability to perform daily activities, keep a journal that describes those limitations in specific terms rather than vague complaints.
Photographs of the vehicle damage, the scene, and your visible injuries add context. Witness statements can shore up liability if the other driver later changes their story. Expert opinions, such as those from a treating physician or an accident reconstruction specialist, can be powerful when the insurer disputes causation or severity. In short, the stronger and more organized your evidence, the harder it is for the insurer to justify a low offer.
If you are unsure whether your documentation is complete or whether you even have a viable claim, a free case evaluation can help you assess your options before you negotiate with the insurer. You can also read more about filing a claim for an underinsured motorist accident to understand how these cases are evaluated in practice.
Common Insurer Tactics in Uninsured and Underinsured Motorist Claims
Insurers handle thousands of UM and UIM claims every year, and they have refined their playbook. One common tactic is to delay. The longer a claim stays open, the more likely a victim is to accept a low offer out of financial pressure. Another tactic is to dispute the extent of your injuries by pointing to pre-existing conditions, minor property damage, or gaps in treatment. A third is to argue that the at-fault driver had enough coverage, which would eliminate the UIM claim entirely.
Insurers also use recorded statements strategically. A seemingly friendly adjuster may ask questions designed to elicit answers that can later be used to reduce the claim, such as whether you have seen a doctor yet or whether you felt fine immediately after the crash. You are generally required to cooperate with your insurer, but cooperation does not mean volunteering information that hurts your claim. It is reasonable to consult an attorney before giving a recorded statement in a UM or UIM case.
Another tactic involves the consent-to-settle clause found in many policies. This clause says you cannot settle with the at-fault driver's insurer without your own insurer's consent, or you risk losing your UIM benefits. If you receive a settlement offer from the other driver's carrier, do not sign anything before confirming how it affects your UIM claim. A misstep here can wipe out the very coverage you paid for.
How an Attorney Can Strengthen Your Claim
You are not legally required to hire an attorney for a UM or UIM claim, but the complexity of these cases often makes representation worthwhile. An experienced personal injury attorney understands the interplay between the at-fault driver's policy, your own policy, state insurance regulations, and the arbitration provisions that many UM and UIM policies contain. That knowledge can prevent costly mistakes and increase the likelihood of a full recovery.
Attorneys also bring resources that individual claimants typically lack. They can retain medical experts to establish causation and future care needs, obtain accident reconstruction reports, and calculate damages that include pain and suffering, emotional distress, and loss of enjoyment of life. They can negotiate with the insurer from a position of strength and, if necessary, pursue arbitration or litigation. Many personal injury attorneys work on a contingency fee basis, meaning you pay nothing upfront and the fee comes out of the recovery. Platforms like LegalCaseReview provide educational analysis of personal injury law and litigation trends, which can help you understand how your case fits into the broader legal landscape.
Choosing the right attorney also matters. Look for someone with specific experience in UM and UIM claims in your state, a track record of results, and a willingness to explain the process clearly. FreeLegalCaseReview.com connects injured individuals with qualified mass tort and personal injury attorneys through a free, confidential case evaluation process, and its patented attorney selection process is designed to identify top legal professionals. Requesting a complimentary case assessment costs nothing and carries no obligation to retain anyone.
Deadlines, Stacking, and Other Rules That Affect Recovery
Every state imposes a statute of limitations on personal injury claims, and UM and UIM claims often have their own contractual deadlines. Missing these deadlines can permanently bar your claim, no matter how strong the evidence. Some policies require notice within a specific number of days after the crash, and some require that you demand arbitration within a set period. Do not assume you have years to act. Confirm the deadlines that apply to your policy and your state as early as possible.
Another rule that can significantly affect recovery is stacking. Stacking allows you to combine UM or UIM limits from multiple policies or multiple vehicles on the same policy. For example, if you have two vehicles insured with $50,000 UIM limits each, stacking might make $100,000 available. Some states permit stacking by law, some prohibit it, and some enforce policy language that limits or allows it. Whether stacking applies in your case can change the value of your claim dramatically.
Other rules to consider include whether your state requires UM and UIM coverage or makes it optional, whether your policy offsets UIM benefits by the amount the at-fault driver paid, and whether you are entitled to recover attorney fees if the insurer acts in bad faith. Understanding these rules is not something most crash victims can do alone, which is why consulting a qualified attorney early is often the smartest step.
Steps to Take Right Now After a Crash With an Uninsured or Underinsured Driver
The actions you take in the days and weeks after a crash shape the strength of your UM or UIM claim. Start by calling the police and obtaining a report, even if the other driver seems cooperative. Exchange information, take photographs, and collect contact details from witnesses. Seek medical attention promptly, not only for your health but also to create a documented link between the crash and your injuries. Notify your own insurer and confirm your UM and UIM limits. Keep every document, including bills, receipts, and correspondence with insurers.
Avoid posting about the crash on social media, and do not give a recorded statement to the at-fault driver's insurer without legal guidance. If the other driver's insurer offers a quick settlement, treat it with suspicion; early offers are often far below fair value. Finally, consider a free case evaluation to understand your rights and options before you sign anything or accept a check.
Uninsured and underinsured motorist claims after a crash are not simple, but they are often the only path to full compensation when the at-fault driver cannot pay. The coverage exists for exactly this situation, and with careful documentation, informed negotiation, and the right legal support, you can pursue the recovery you deserve.