
Settle Before Medical Treatment Ends: A Risky Move?
Should you accept a settlement before finishing medical treatment? Waiting protects your future medical costs. Call (833)-248-4565 for a free case review.
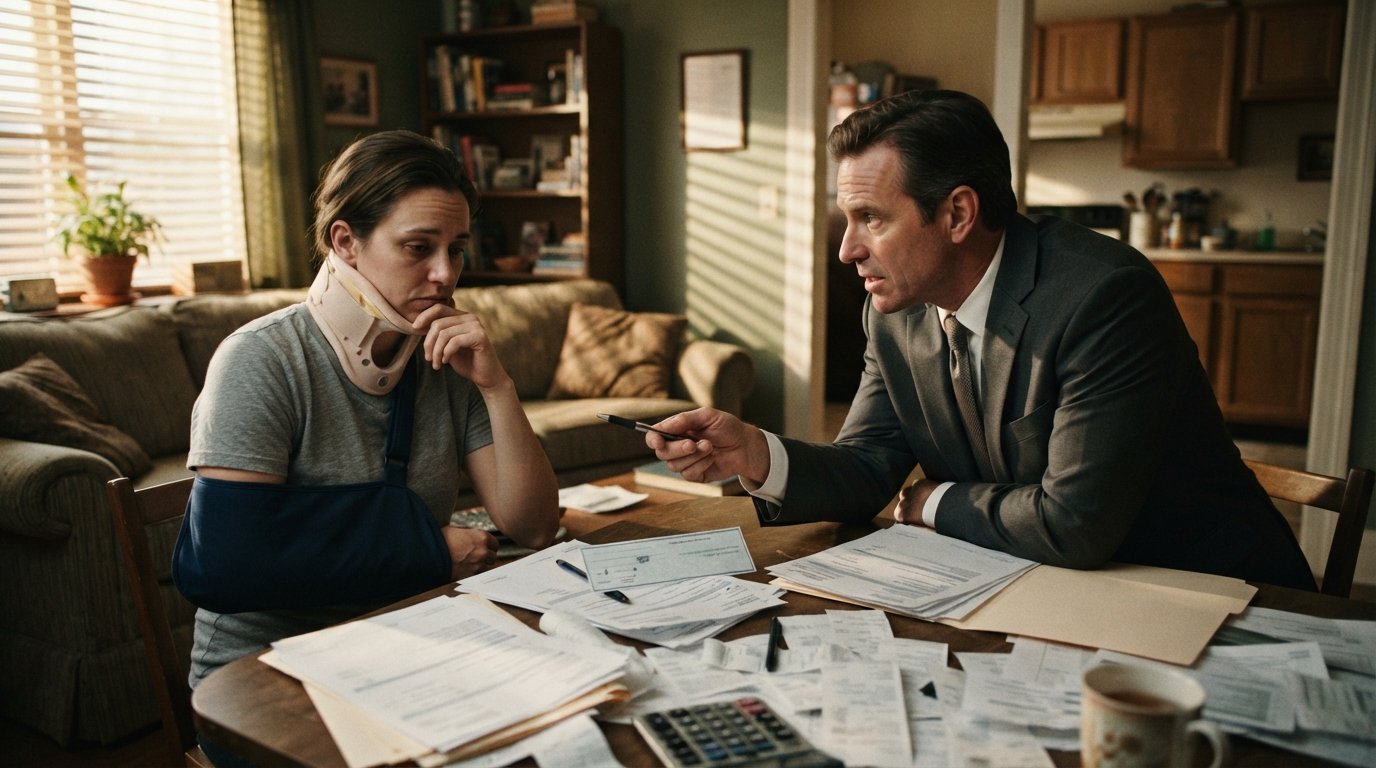
You are hurt, the bills are piling up, and the insurance adjuster is waving a check in your face. The offer sounds decent, maybe even generous, and the pressure to just make it all go away is immense. But before you sign on the dotted line, you need to ask a critical question: should you accept a settlement before finishing medical treatment? The answer is almost always no, and understanding why could be the difference between a fair recovery and a lifetime of unpaid medical bills.
The moment you accept a settlement, you are signing a release that waives your right to seek any further compensation from the at-fault party. That includes future medical care, lost wages, and pain and suffering that may not yet have manifested. If your injuries are not fully healed or if your doctor has not yet reached maximum medical improvement (MMI), you have no way of knowing what your final costs will be. Settling early is like buying a house without an inspection: you might get a deal, but you are also taking on all the hidden risks.
The Hidden Dangers of Settling Before You Are Fully Healed
The biggest risk in any early settlement is future medical costs. After an accident, your initial diagnosis may only scratch the surface. Soft tissue injuries, traumatic brain injuries, and spinal cord damage often evolve over weeks or months. What seems like a simple strain could turn into a herniated disc requiring surgery. A concussion might lead to long-term cognitive issues. If you settle before these conditions fully develop, you will be on the hook for every co-pay, prescription, and therapy session down the road.
Insurance adjusters know this, and they often push for quick settlements precisely because they want to cap their exposure. They may tell you that the offer is only good today, or that waiting will only hurt your case. Do not be fooled. In most states, the statute of limitations for personal injury claims is two to three years, so you have time. The adjuster's urgency is a tactic, not a deadline set by law.
Another major risk is the release language itself. When you sign a settlement agreement, you are typically signing a full and final release. That document will contain language waiving all known and unknown claims related to the accident. Even if you develop a new injury later, you will have no legal recourse. Courts generally uphold these releases unless there is clear fraud or mutual mistake, which is very hard to prove. So if you have any doubt about your recovery, do not sign.
Consider the story of a client who settled a car accident claim for $15,000, thinking his neck pain was just whiplash. Six months later, an MRI revealed a herniated disc that required surgery costing over $50,000. Because he had already signed a release, he was stuck with the bills. This scenario is all too common, and it underscores why finishing medical treatment before settling is crucial.
Why Future Medical Costs Are the Biggest Threat to Your Recovery
When you settle a claim, you are essentially selling your right to future compensation for a lump sum today. The insurance company is betting that your injuries will heal and that you will not need ongoing care. You are betting that the lump sum will cover everything. But without a complete picture of your medical future, that bet is a gamble you cannot afford to lose.
To accurately value a claim, you need to know the full extent of your injuries, the expected duration of treatment, and the cost of that treatment. This is why doctors use the term maximum medical improvement (MMI). MMI is the point at which your condition has stabilized and further treatment is unlikely to improve your outcome. Only at MMI can you and your attorney confidently estimate future medical needs, such as surgeries, physical therapy, medications, or assistive devices.
If you settle before MMI, you are essentially guessing. And the insurance company knows you are guessing. They will likely lowball you, knowing that you are not in a position to hold out for more. On the other hand, if you wait until you have a clear prognosis, you can demand compensation for all your past and future medical expenses, lost earning capacity, and pain and suffering. That is how you maximize your recovery.
Here is a simple rule: never accept a settlement until your doctor has declared you at MMI or until you have a firm treatment plan with defined costs. If your doctor says you need surgery, get the surgery before you settle. If you need ongoing physical therapy, get an estimate of the total cost. Only then can you negotiate from a position of strength.
How to Handle Adjuster Pressure and Time-Limited Offers
Insurance adjusters are trained negotiators. Their job is to settle your claim for as little as possible, as quickly as possible. They will use a variety of tactics to get you to sign early. They might tell you that the offer expires in 24 hours, that they are doing you a favor, or that hiring a lawyer will only delay things. Do not let them rush you.
One common tactic is the "recorded statement." The adjuster will ask you to give a recorded statement about the accident. They may sound friendly, but anything you say can be used against you later. Politely decline to give a recorded statement until you have spoken with an attorney. You are not required to give one, and it is almost never in your best interest.
Another tactic is the low initial offer. The adjuster may offer you a few thousand dollars, hoping you will accept it out of desperation. If you refuse, they may increase the offer slightly. This is a game. The best way to counter is to have a clear picture of your damages. Once you know your total medical costs, lost wages, and pain and suffering, you can make a counteroffer that is grounded in evidence. Adjusters respect claimants who know their numbers.
If the adjuster is pressuring you with a time-limited offer, remember that you are in control. You can simply say, "I am still treating, and I will not discuss settlement until I am finished." They may huff and puff, but they cannot force you to settle. In fact, waiting often increases the settlement value because the adjuster knows you are serious and that your injuries are significant.
If you are feeling overwhelmed, consider hiring a personal injury attorney. An attorney can handle all communication with the adjuster, protect you from unfair tactics, and ensure that you do not settle for less than you deserve. Most personal injury attorneys work on a contingency fee basis, meaning you pay nothing upfront and only pay if they win your case. If you are unsure where to start, you can request a free case evaluation from a service like AutoInjuryAccident to connect with a qualified lawyer in your area.
Steps to Value an Unresolved Claim Accurately
If you have decided to wait until you finish medical treatment, you need a plan to value your claim accurately. Here is a step-by-step approach:
- Complete all recommended treatment. Follow your doctor's orders, attend all appointments, and take all prescribed medications. Gaps in treatment can be used by the insurance company to argue that you were not seriously injured.
- Obtain a final prognosis. Ask your doctor for a written report that outlines your injuries, the treatment you received, your current condition, and any future medical needs. This report is the foundation of your claim.
- Calculate your economic damages. Add up all medical bills (past and future), lost wages, and out-of-pocket expenses. Include documentation such as bills, receipts, and pay stubs.
- Document your non-economic damages. Pain and suffering, emotional distress, and loss of enjoyment of life are harder to quantify, but you can keep a journal and gather statements from friends and family.
- Consult with an attorney. An experienced personal injury attorney can review your case, help you understand the full value of your claim, and negotiate with the insurance company on your behalf.
By following these steps, you will be in a much stronger position to negotiate a fair settlement. Remember, the insurance company's first offer is rarely their best offer. They expect you to negotiate, and they have room to increase their offer if you have the evidence to back up your demands.
It is also important to be aware of the risks of stopping medical treatment early. If you stop treatment before you are fully healed, the insurance company will argue that you are not as injured as you claim. They may also use the gap in treatment to reduce your settlement. In our guide on the risks of stopping medical treatment early, we explain how this can jeopardize your claim. Always follow your doctor's advice and continue treatment until you are discharged.
The Bottom Line: Patience Pays Off
Should you accept a settlement before finishing medical treatment? The answer is a resounding no. Settling early is one of the biggest mistakes an injured person can make. It can leave you with unpaid medical bills, ongoing pain, and no legal recourse. By waiting until you have completed treatment and reached maximum medical improvement, you can ensure that your settlement covers all your past and future needs.
Insurance adjusters will try to rush you, but you have the power to say no. Take your time, focus on your recovery, and consult with a personal injury attorney if you need help. Your health and financial future are too important to gamble on a quick settlement. If you are ready to explore your legal options, consider reaching out to a qualified attorney for a free case evaluation. For more information on personal injury claims and to connect with legal professionals, visit FreeLegalCaseReview.com.