
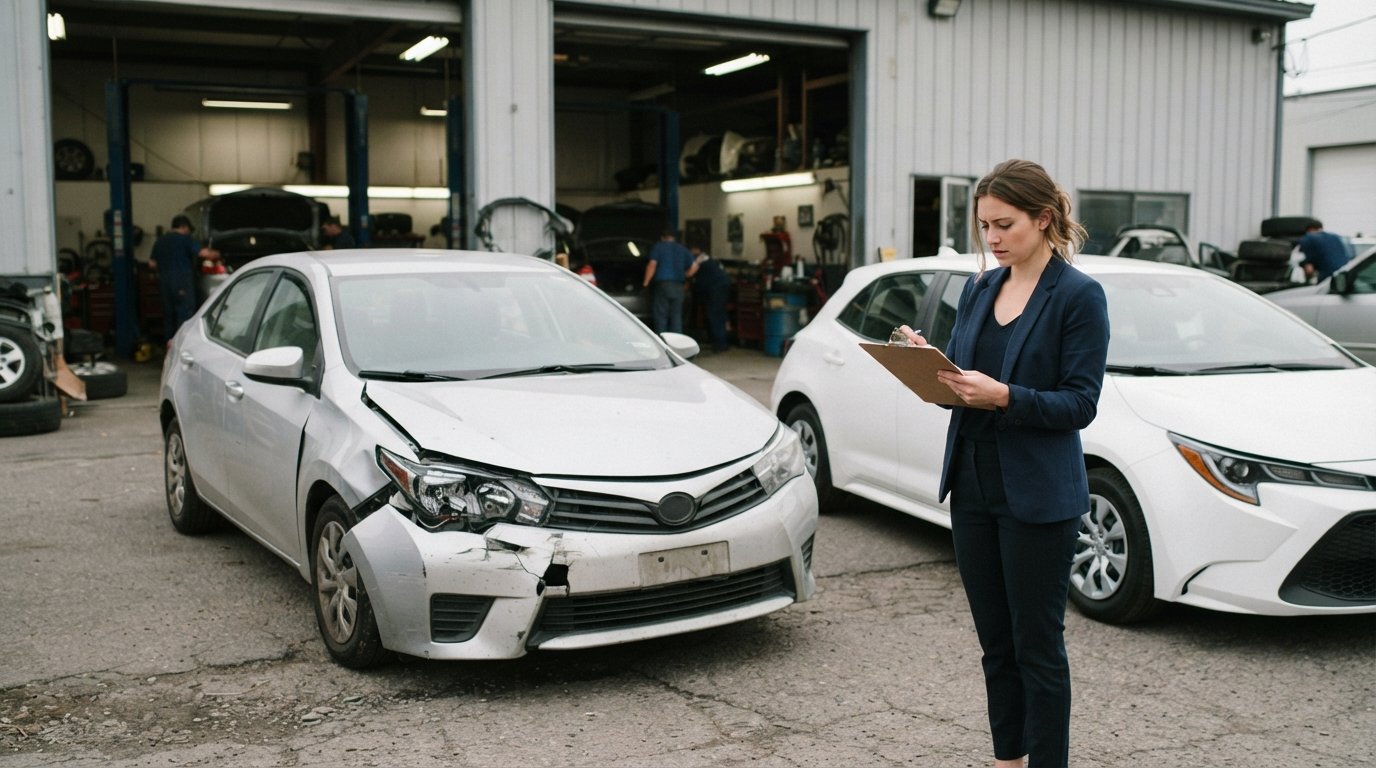
Rental Car and Loss of Use Reimbursement After an Accident
Understand rental car and loss of use reimbursement after an accident. Call (833)-248-4565 for a free case review and protect your claim.
By Max Thompson
Your car is in the shop after a crash, and you are staring at a rental car bill that keeps growing. You may be wondering who is responsible for covering those costs, and whether you can also recover money for the days you were deprived of your vehicle even if you did not rent a replacement. Understanding rental car and loss of use reimbursement after an accident is essential to protecting your financial recovery. This guide breaks down the key differences between these two types of damages, explains who pays, and shows you how to document your claim so you do not leave money on the table.
Loss of Use vs. Rental Reimbursement: What Is the Difference?
Many people use the terms "loss of use" and "rental reimbursement" interchangeably, but they are not the same thing. Rental reimbursement is a specific, out-of-pocket expense you incur when you rent a substitute vehicle while yours is being repaired. Loss of use is a broader legal concept that compensates you for the deprivation of your vehicle's use, regardless of whether you actually rented a car. In other words, loss of use damages compensate you for the inconvenience and lost utility you suffered because you did not have access to your vehicle.
Insurance companies often try to limit loss of use payments to the actual cost of a rental, but in many jurisdictions, you can recover loss of use even if you did not rent a car. For example, if you borrowed a friend's car or used public transportation, you may still be entitled to a reasonable daily rate for the loss of your vehicle's use. The key is to prove the reasonable rental value of your vehicle for the period it was out of commission. This distinction matters because the at-fault party's insurer may push back on paying loss of use without a rental receipt, but that does not mean you are not entitled to it.
To maximize your recovery, you should understand both concepts and how they interact. Rental reimbursement is typically a special damage that requires proof of actual expense. Loss of use is a general damage that can be established through testimony, market rates, and other evidence. In many states, you can claim both, but you cannot double-recover for the same period. If you rented a car, the rental cost becomes the measure of your loss of use. If you did not rent, you can still seek loss of use based on the reasonable rental value of your vehicle.
Who Pays for Rental Car and Loss of Use After an Accident?
Determining who pays for your rental car and loss of use depends on several factors, including fault, your insurance coverage, and the laws of your state. The at-fault driver's liability insurance is typically the primary source of payment for these damages. However, the at-fault insurer may not immediately accept responsibility, and you may need to use your own collision coverage or rental reimbursement coverage to get into a rental car quickly. Understanding the options can help you avoid paying out of pocket while waiting for the claim to resolve.
Here are the main sources of payment to consider:
- At-fault driver's liability insurance: If the other driver is clearly at fault, their insurer should pay for your rental car and loss of use as part of your property damage claim. However, some insurers will only pay after you submit receipts and may dispute the daily rate or the length of the rental.
- Your own collision coverage: If you have collision coverage, you can file a claim with your own insurer to get your car repaired and often secure a rental car through your rental reimbursement coverage. Your insurer will then seek reimbursement from the at-fault party through subrogation. This is often the fastest way to get into a rental.
- Your rental reimbursement coverage: This is an optional add-on to your auto policy that pays for a rental car while your vehicle is being repaired, up to a daily limit and a maximum total. It is not liability coverage, but it can bridge the gap while fault is being determined.
- The other party directly: In some cases, you may be able to pursue the at-fault driver personally, but this is rare and usually only if they are uninsured or underinsured and you have no other options.
It is important to note that liability insurance does not always kick in immediately. The at-fault insurer may need to investigate the accident before accepting liability. In the meantime, you are responsible for mitigating your damages, which means you should not rent an excessively expensive car or keep it longer than necessary. If you have rental reimbursement coverage, use it, and then let your insurer subrogate against the at-fault party. If you do not have that coverage, you may need to pay out of pocket and seek reimbursement later. Keep in mind that some states have laws that require insurers to pay for loss of use within a certain timeframe, but these vary widely.
If you are unsure about your rights or the at-fault insurer is giving you the runaround, seeking a free case evaluation can help you understand your options. A qualified attorney can review your situation and advise you on the best course of action to recover rental car and loss of use reimbursement after an accident.
How to Document Rental Costs and Loss of Use
Documentation is the backbone of any successful claim for rental car and loss of use reimbursement after an accident. Without proper records, the insurer can easily dispute your expenses or deny your loss of use claim altogether. You need to show that the rental was necessary, that the duration was reasonable, and that the daily rate was fair. Similarly, for loss of use, you need evidence of the reasonable rental value of your vehicle and the exact period it was out of service.
Start by keeping every receipt and contract related to your rental car. This includes the rental agreement, itemized bills, and proof of payment. Also, keep a record of the dates your car was in the shop, including the repair estimate, work orders, and the final invoice showing the date repairs were completed. If your car was declared a total loss, the loss of use period typically ends when the insurer makes a reasonable settlement offer, not when you actually buy a new car. You should also document any mileage you put on the rental, as some policies have mileage limits or require you to pay for excess mileage.
For loss of use, you can gather evidence of the reasonable daily rental value of your vehicle. This can be done by obtaining quotes from rental agencies for a similar make and model. You can also use online tools or ask a local rental company for a written estimate. If you did not rent a car, keep a log of the days you were without your vehicle and how you managed transportation (for example, receipts for public transit, rideshare, or borrowed vehicle). This helps demonstrate that you indeed suffered a loss of use.
Here is a checklist to help you stay organized:
- Rental receipts and contract: Keep the original rental agreement and all payment receipts.
- Repair records: Save the repair estimate, work orders, and final invoice with dates.
- Total loss documentation: If your car is totaled, keep the settlement offer and correspondence with the insurer.
- Proof of reasonable rental value: Obtain quotes from rental agencies for a comparable vehicle.
- Alternative transportation records: If you did not rent, keep receipts for public transit, rideshare, or a written statement about borrowing a car.
Presenting a well-organized file to the adjuster can significantly speed up your claim and reduce the chance of disputes. Remember that the burden of proof is on you to show that your expenses were reasonable and necessary. If you are working with an attorney, they can help you compile this evidence and negotiate with the insurer.
How Total Loss Claims Change Loss of Use Calculations
When your vehicle is declared a total loss, the calculation of loss of use becomes more complex. In a total loss, the car is not repairable, so there is no repair period to measure. Instead, loss of use is typically calculated from the date of the accident until the date the insurer makes a reasonable settlement offer for the actual cash value of your vehicle. The rationale is that once the insurer offers a fair settlement, you have the means to replace your vehicle, so the loss of use ends.
However, insurers often delay making a settlement offer, and they may undervalue your car. If the insurer takes weeks to make an offer, you may be entitled to loss of use for that entire period. You should document all communication with the insurer, including the date you provided all necessary information and the date they made an offer. If the offer is unreasonably low, you can argue that the loss of use period should continue until a fair offer is made. Some states have specific rules about this, so it is wise to consult with an attorney if you are facing a total loss claim.
Another wrinkle in total loss claims is that rental reimbursement may be limited by your policy's rental reimbursement coverage, which typically has a maximum daily and total limit. If you have rental reimbursement coverage, it will only pay for a rental car for a certain number of days, regardless of how long it takes to settle the total loss. In that case, you may need to rely on the at-fault party's liability insurance to cover the gap. If the at-fault insurer delays, you may be able to recover additional loss of use damages from them.
If you are dealing with a total loss and the insurer is not cooperating, consider reaching out to a legal professional. A free case review can help you understand your rights and whether you are entitled to additional compensation for loss of use. You can also learn more about navigating a personal injury car accident claim by visiting our legal roadmap, which provides a step-by-step overview of the claims process.
Common Pitfalls to Avoid When Claiming Rental Car and Loss of Use Reimbursement
Even with the right documentation, many claimants run into problems when seeking rental car and loss of use reimbursement after an accident. One common mistake is renting a vehicle that is far more expensive than what you were driving. Insurers will only pay for a comparable vehicle, so if you upgrade to a luxury car, you will likely be stuck with the difference. Another pitfall is failing to mitigate your damages by keeping the rental car longer than necessary. Once your car is repaired, you should return the rental promptly, or the insurer may dispute the extra days.
Another issue is not notifying the at-fault insurer of your rental needs early on. Some insurers require pre-approval before you rent a car, and if you fail to get it, they may refuse to reimburse you. Always communicate in writing and keep a record of any approvals or denials. Additionally, be wary of signing a release or settlement agreement that includes a waiver of loss of use. Once you sign, you may lose your right to claim additional damages.
Finally, do not ignore your own insurance policy's requirements. If you have rental reimbursement coverage, you must follow the claims process, which may include providing a copy of the rental agreement and receipts. Failing to do so could result in a denial. If you are unsure about how to proceed, a free case evaluation with a qualified attorney can provide clarity and help you avoid these pitfalls.
When you are ready to explore your legal options, consider using a service like CheapInjuryLawyer to connect with experienced personal injury attorneys who can assist with your claim. They offer free, confidential case reviews and can help you pursue the compensation you deserve, including rental car and loss of use reimbursement after an accident.
In summary, rental car and loss of use reimbursement after an accident are two distinct but related damages that can significantly impact your financial recovery. By understanding the difference, knowing who pays, documenting your expenses thoroughly, and being aware of how total loss claims affect your claim, you can maximize your chances of a fair settlement. If you encounter resistance from insurers or simply want professional guidance, do not hesitate to seek a free case evaluation. Taking the right steps early can make all the difference in getting you back on the road without unnecessary financial strain.