
Life Care Plan in Catastrophic Injury Litigation Explained
Learn how a life care plan in catastrophic injury litigation explained values future care needs. Call (833)-248-4565 for a free case evaluation.
By Lucian Northwood
When a catastrophic injury permanently alters someone's life, the true financial cost extends far beyond the initial hospital bills. Families supporting a severely injured person quickly learn that future medical care, home modifications, assistive technology, and daily attendant services can add up to millions of dollars over a lifetime. The tool that captures these future needs in a courtroom is known as a life care plan, and understanding how it works is essential for anyone navigating catastrophic injury litigation. This guide explains the life care plan in catastrophic injury litigation in plain terms, from who prepares it and what it costs to how defense experts attack it and why it often becomes the centerpiece of settlement negotiations.
What a Life Care Planner Does and Who Pays for the Report
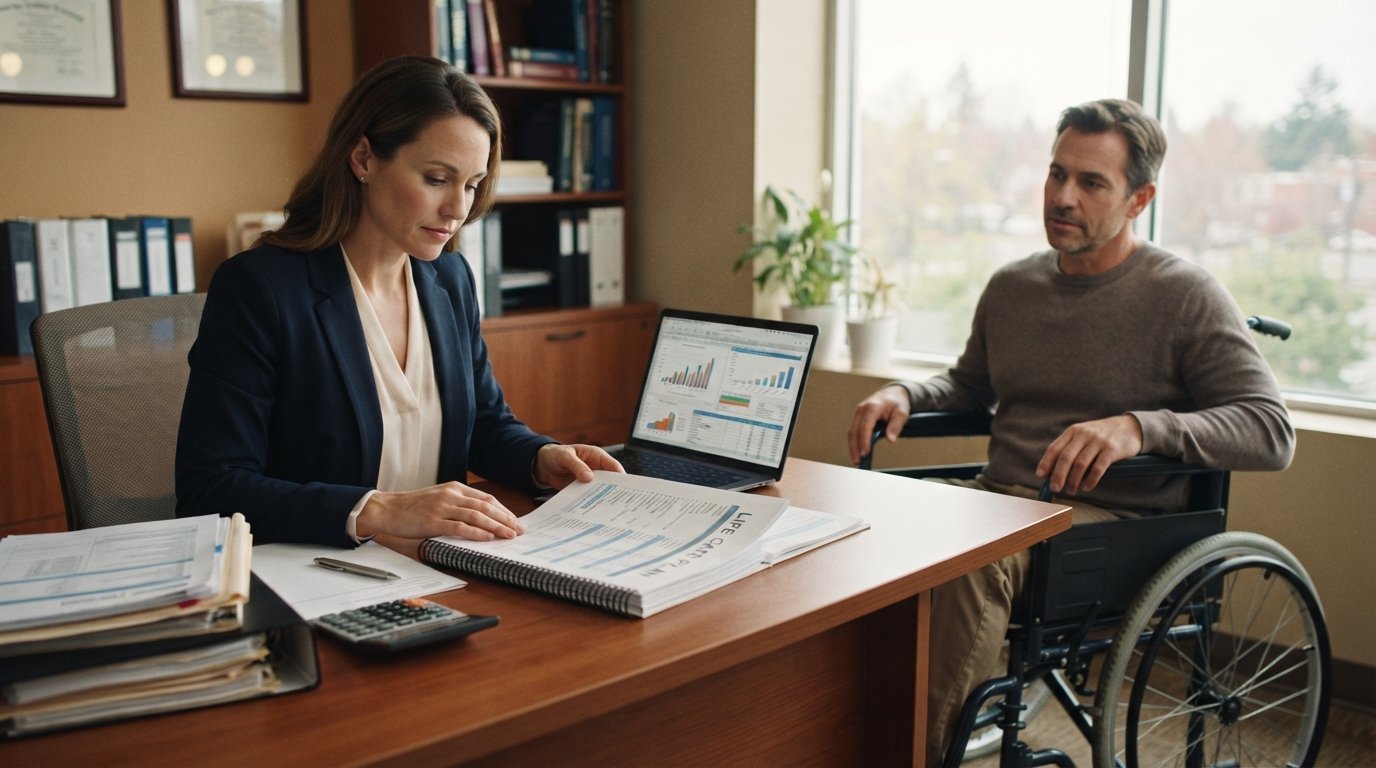
A life care planner is typically a rehabilitation professional, nurse, or vocational expert with specialized training in assessing the long-term needs of individuals with catastrophic injuries. This expert conducts a thorough evaluation that includes reviewing medical records, interviewing the injured person and family members, consulting with treating physicians and therapists, and researching the costs of recommended services in the injured person's geographic area. The result is a comprehensive, itemized document that projects every medical and non-medical need the injured person will likely require for the rest of their life, along with the associated costs.
The life care plan covers a wide range of categories, and each one is supported by evidence such as physician prescriptions, therapist recommendations, and market research on pricing. Common categories include:
- Medical care: physician visits, hospitalizations, surgeries, and medications
- Rehabilitation therapies: physical, occupational, and speech therapy
- Attendant care: home health aides, nursing services, and supervision
- Home and vehicle modifications: wheelchair ramps, widened doorways, accessible bathrooms, and adaptive transportation
- Assistive equipment and technology: wheelchairs, communication devices, and mobility aids
- Future education and vocational support, when applicable
Who pays for the life care plan depends on the stage of the case. In pre-litigation, the injured person's attorney often advances the cost, which can range from several thousand to over ten thousand dollars depending on complexity. In many arrangements, the expert is paid on a contingency basis, meaning the fee is repaid from the eventual settlement or verdict. Defense firms may also commission their own life care plans, or they may rely on in-house experts to critique the plaintiff's plan. Understanding who is paying for the report helps families evaluate potential bias and prepare for the adversarial nature of litigation.
For families trying to make sense of the broader legal process, resources like what a catastrophic injury lawyer does for severe accident victims can clarify how an attorney coordinates experts, including life care planners, to build a compelling case. The planner's work is rarely done in isolation; it is part of a team effort that includes treating physicians, economists, and vocational specialists.
Cost Categories That Drive the Numbers
The dollar figure at the bottom of a life care plan is not a random estimate. It is built from specific cost categories, each tied to the injured person's medical condition and prognosis. The largest drivers tend to be attendant care, home modifications, and durable medical equipment, but every category matters. A planner will typically project costs on an annual basis and then multiply by the injured person's remaining life expectancy, adjusting for inflation and the cost of medical care increases.
Attendant care is often the single largest line item. For a person with a traumatic brain injury or spinal cord injury, round-the-clock supervision or assistance with daily activities may be required. The planner calculates the number of hours per day, the hourly rate for aides or nurses in the local market, and the number of years the care will be needed. Similarly, home modifications can include structural changes like roll-in showers, stair lifts, and expanded doorways, and the planner obtains contractor estimates to support these figures. Equipment costs include wheelchairs, pressure-relief cushions, ventilators, and communication devices, each with a replacement schedule based on the manufacturer's lifespan estimates.
Therapy and medical follow-up are also projected. Physical therapy may be needed indefinitely to maintain function and prevent complications, and physician visits, imaging, and medications are scheduled according to the treating doctors' recommendations. The planner must account for the fact that some costs will change over time: a child may need different equipment as they grow, and an adult may develop secondary conditions that require additional care. A well-constructed plan builds in contingencies for these changes, which is one reason why defense experts often challenge the projections as speculative.
Families often wonder how these numbers translate into a settlement demand. The life care plan provides the foundation for the economic damages portion of the claim, which is then combined with non-economic damages like pain and suffering. Without a detailed plan, future medical costs are easily underestimated, leaving the injured person undercompensated for decades of care.
How Defense Experts Challenge Life Care Plan Figures
Defense attorneys rarely accept a life care plan at face value. They employ a range of strategies to attack the plan's credibility and reduce the projected costs. One common approach is to argue that the plan is inflated because it includes services the injured person does not actually need or that are not supported by the treating physicians' records. Defense experts may testify that a lower level of care, such as family-provided care instead of professional attendants, is appropriate. They may also challenge the planner's methodology, claiming that the expert failed to consider the injured person's pre-existing conditions or made unreasonable assumptions about life expectancy.
Another tactic is to question the planner's qualifications or bias. Defense counsel may point out that the planner was hired by the plaintiff's attorney and paid on a contingency basis, suggesting a motive to inflate costs. They may present their own life care planner who offers a more conservative estimate, creating a battle of the experts that the jury must resolve. In some cases, the defense will argue that the plaintiff's plan duplicates services already covered by insurance or government benefits, although collateral source rules vary by state.
To withstand these challenges, the plaintiff's life care plan must be meticulously documented. Each recommendation should be tied to a specific medical record or physician prescription, and the cost estimates should be supported by reliable sources such as medical equipment vendors or home care agencies. The planner should also be prepared to explain the rationale for every line item and to adjust the plan if new medical information emerges. Attorneys who understand these defense tactics can prepare their experts for cross-examination and shore up weaknesses before trial.
For families, it is important to know that a life care plan is not a static document. It can be updated as the injured person's condition changes, and a revised plan may be necessary if new treatments become available or if the person's needs increase. Keeping the plan current strengthens its credibility and ensures that the settlement or verdict reflects the true cost of care.
Why the Life Care Plan Is Central to Negotiating a Fair Settlement
In catastrophic injury cases, the life care plan often becomes the anchor for settlement negotiations. Insurance adjusters and defense counsel know that a well-supported plan can persuade a jury to award a large verdict, so they are motivated to settle before trial if the plan is credible. The plan also serves as a roadmap for mediation, helping both sides understand the range of future costs and identify areas of agreement. Without a plan, negotiations can devolve into guesswork, and the injured person risks accepting a lump sum that runs out long before their care needs end.
A strong life care plan does more than list costs; it tells a story about the injured person's future. It paints a picture of the daily challenges they will face and the resources required to maintain dignity and quality of life. When presented effectively, this narrative can be compelling to a jury and can pressure insurers to offer a fair settlement. Attorneys often use the plan in conjunction with an economist's report that calculates the present value of future costs, making the numbers easier for a jury to grasp.
For families who are considering legal action, it is important to understand that the life care plan is just one piece of the puzzle. Choosing the right attorney and building a team of experts are critical steps. Resources like AttorneyLawsuit provide additional information on legal disputes involving attorneys and can help consumers understand their rights when navigating complex litigation. Additionally, platforms like FreeLegalCaseReview.com offer free case evaluations to connect injured individuals with qualified attorneys who can assess whether a life care plan is appropriate for their situation.
In many cases, the life care plan also plays a role in structuring the settlement. Some settlements include a Medicare Set-Aside arrangement to preserve future Medicare benefits, and the life care plan helps determine the amount needed for that set-aside. Attorneys may also recommend a structured settlement annuity to ensure that funds are available over time, rather than a single lump sum that could be mismanaged. These financial decisions are complex, and having a detailed plan provides the data needed to make informed choices.
Finally, families should be aware that the life care plan can influence not only the amount of the settlement but also the timing. Insurers may be more willing to negotiate early if they see a credible plan that demonstrates a high risk of a large verdict. Conversely, a weak or poorly documented plan can invite lowball offers and prolong the case. Investing in a thorough plan upfront often pays off in the long run.
If you are supporting a loved one after a catastrophic injury, understanding the life care plan is a crucial step toward securing the resources they will need. A free, confidential case evaluation with an experienced attorney can help you determine whether a life care plan should be part of your legal strategy. With the right team and a well-built plan, you can pursue the compensation necessary to provide for a lifetime of care.