
How to Protect Your Claim When Adjusters Ask for a Recorded Statement
A recorded statement can make or break your injury claim. Learn how to protect your claim when adjusters ask for a recorded statement. Call (833)-248-4565 for help.
By Aurelia Finch
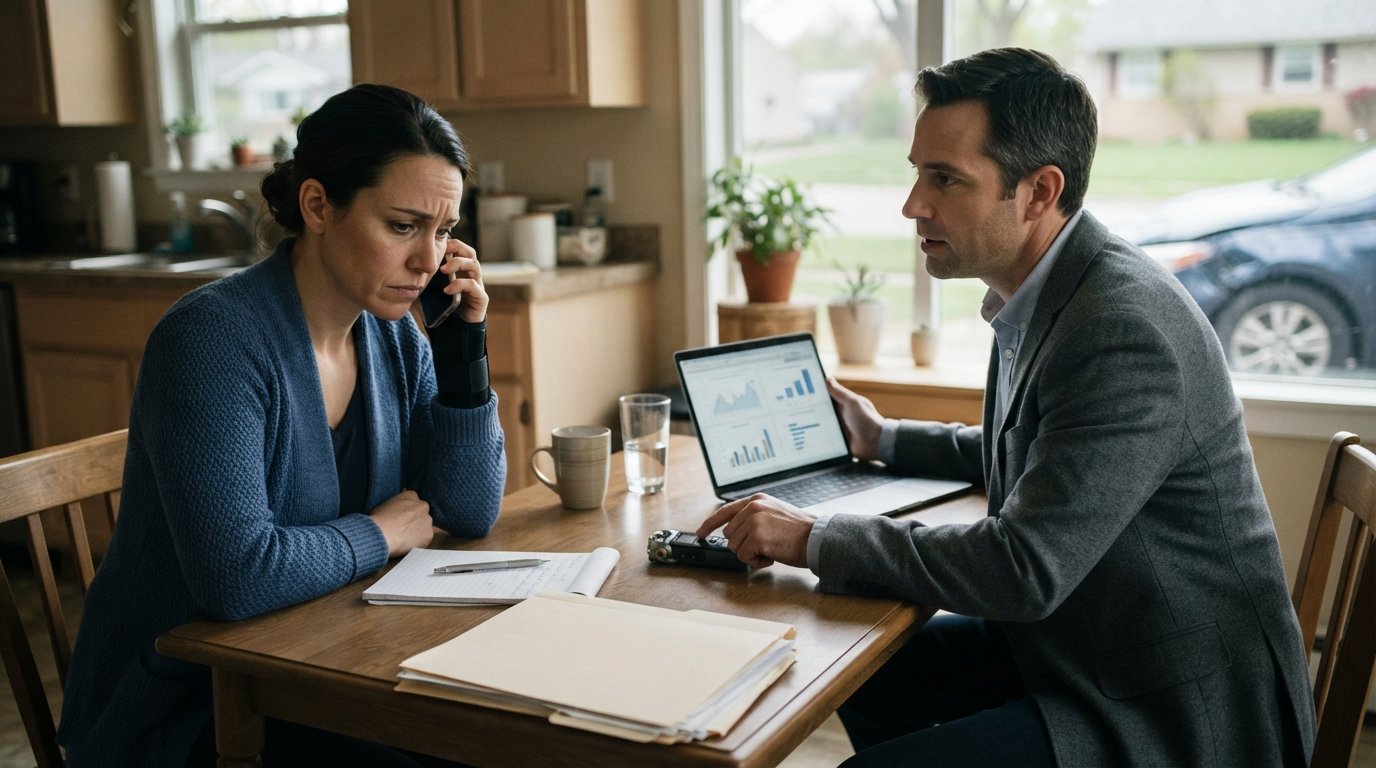
After a car accident, the phone rings quickly. A friendly voice identifies themselves as an insurance adjuster and asks if you have a few minutes to give a recorded statement. They sound helpful, maybe even concerned. But that call is not a casual conversation. It is a formal evidence-gathering step that can shape the value of your injury claim for months or years. Knowing how to protect your claim when adjusters ask for a recorded statement is one of the most important skills an injured person can learn, because a single careless answer can reduce or even eliminate your compensation.
Insurance companies train adjusters to extract information that benefits the carrier. They are not neutral fact-finders. The recorded statement is a tool designed to lock you into a version of events, catch inconsistencies, and create admissions you may not realize you made. This article explains why adjusters ask for recordings so early, what they are really evaluating, whether you are legally required to cooperate, and exactly how to handle the request without damaging your case. The guidance here is educational and not legal advice; for situation-specific direction, a free case evaluation with a qualified attorney is the safest next step.
Why Adjusters Request a Recorded Statement So Early
Speed is deliberate. The adjuster often calls within 24 to 72 hours of the crash, before you have seen all your medical providers, before the police report is finalized, and before you have had time to think carefully about what happened. That timing is not accidental. Early in the process, you are likely in pain, distracted, and unfamiliar with how insurance claims work. Adjusters know that people in that state tend to talk more than they should.
There is also a documentation motive. A recorded statement creates a permanent record that the insurer can replay, transcribe, and compare against later statements, medical records, and depositions. If your description of the accident shifts even slightly, the insurer will argue that your credibility is compromised. If you say you feel fine on the recording and later claim a serious back injury, the insurer will point to that early statement as proof that you were not hurt.
Finally, the early call is a triage tool. The adjuster is deciding whether your claim looks like a quick low settlement or a serious case that needs reserves. A claimant who sounds confused, guesses at details, or downplays symptoms signals a low-value file. The recording helps the carrier calibrate its strategy before you have any representation.
What the Adjuster Is Really Evaluating During the Call
The adjuster is not just collecting facts. They are evaluating you. Every question is designed to test something specific, and understanding those tests helps you see why casual answers are dangerous.
First, the adjuster is testing consistency. They will ask the same fact in several ways, sometimes out of order, to see if your story holds together. Second, they are testing for speculation. Questions like "How fast was the other car going?" or "Did you see them coming?" invite guesses. A guess on a recording becomes a statement you must defend later. Third, they are testing for pre-existing conditions and prior claims. Questions about your health history, previous accidents, and past injuries are designed to surface anything the carrier can use to argue your current injuries are not new.
Fourth, they are testing your demeanor. Adjusters note whether you are angry, confused, overly eager, or unsure. They may also probe for admissions of fault, even partial fault, because many states reduce compensation proportionally when the injured person shares responsibility. Fifth, they are testing your medical status. Questions about how you feel, whether you went to the emergency room, and whether you missed work are compared later against medical records and wage loss documentation. Any gap between your recorded words and your documented losses becomes ammunition for the insurer.
The Real Risks of a Recorded Statement
The most common trap is speculation. When an adjuster asks how fast the other driver was going or how far away they were when you first noticed them, the honest answer is often "I do not know." But injured people, wanting to be helpful, estimate. That estimate becomes a fixed data point. If the physical evidence later suggests a different speed or distance, the insurer will argue that your recollection is unreliable.
The second risk is inconsistency. Your memory of the crash will naturally change as you recover, review the police report, and speak with witnesses. A recording freezes your earliest, least informed version of events. Later, when you remember additional details or your injuries are fully diagnosed, the insurer will compare the two accounts and claim you are embellishing. Even innocent differences in wording can be framed as dishonesty.
The third risk is the casual admission. Adjusters are skilled at asking seemingly harmless questions that produce damaging answers. "You were wearing your seatbelt, right?" "You did not go to the hospital that day, did you?" "You have had back pain before, correct?" A simple yes or no can be used to argue comparative fault, failure to mitigate, or pre-existing injury. The fourth risk is the friendly trap: the adjuster sounds sympathetic, you relax, and you volunteer information about your day, your prior accidents, or your doubts about the case. Everything you say is preserved.
Are You Legally Required to Give a Recorded Statement?
The answer depends on who is asking. Your own insurance company is a contractual counterparty. Most auto policies contain a cooperation clause requiring the insured to cooperate with the insurer's investigation. That clause may obligate you to provide information, but it does not necessarily require a recorded statement, and it does not require you to give one immediately without preparation. The scope of the duty varies by policy language and state law, which is why reviewing your policy with an attorney is worthwhile before you agree to anything.
The other driver's insurer is a different matter. That company has no contract with you. You generally have no legal obligation to give a recorded statement to a third-party adjuster, and you can decline or defer the request. Many people do not realize this. They assume that because the other driver's insurance company is handling the claim, they must comply. They do not. A polite deferral is almost always the safer path.
Even with your own insurer, you can often satisfy the cooperation requirement by providing the facts in writing, through your attorney, or after you have had time to review the police report and your medical records. The key is not to refuse cooperation outright but to control the timing and format of the information you provide.
How to Politely Decline or Defer the Request
You do not need to be confrontational. A short, calm response protects your rights without creating unnecessary friction. The goal is to buy time, avoid committing to details you do not yet know, and route the conversation through a professional who understands the process.
Here is a simple framework you can use when an adjuster calls:
- Thank them and confirm the request. "Thank you for reaching out. I understand you would like a recorded statement."
- State that you are not prepared to give one today. "I am still recovering and have not reviewed the police report or my medical records, so I am not in a position to give a recorded statement right now."
- Offer a written alternative or a future conversation. "I am happy to provide the basic facts in writing, or we can revisit this once I have had a chance to speak with an attorney."
- Avoid explaining, arguing, or apologizing. Keep it brief. Do not volunteer details about your injuries, your treatment, or your plans.
- Document the call. Write down the date, time, adjuster name, company, and what was requested and said.
If the adjuster pushes back, repeats the request, or implies that refusing will hurt your claim, do not engage. You can say, "I understand your position. I am not refusing to cooperate; I am asking to provide the information in a different way or at a later time." Then end the call politely. You are not required to debate. If you have retained counsel, direct all future communications to the attorney's office.
For claimants who want a structured, no-pressure way to review their situation before speaking with an insurer, a quick free injury consultation can clarify your rights and connect you with an attorney who handles recorded statement issues regularly. That conversation costs nothing and can prevent costly mistakes.
What to Do If You Decide to Give a Statement
Sometimes a statement is unavoidable, for example when your own insurer insists and your policy clearly requires cooperation. If you decide to proceed, prepare carefully. Review the police report, your medical records, and any photos or witness information first. Write out a short timeline of the crash and your treatment. Then keep your answers narrow and factual.
Answer only the question asked. Do not volunteer extra information, do not guess at speeds, distances, or times you do not actually know, and do not describe your injuries as "fine" or "minor" if you are still being treated. If you do not know something, say so: "I do not know" or "I do not recall" is a complete and acceptable answer. If a question assumes something you disagree with, correct the premise before answering. If you need a break, ask for one. You can also request that the statement be taken with your attorney present, though the adjuster may decline; if so, that is useful information about how the carrier intends to handle your claim.
After the call, ask for a copy of the recording or transcript. Insurers do not always provide it voluntarily, but a written request is reasonable and can be important if a dispute arises later. Keep your own notes of what you said and when.
Common Adjuster Tactics to Recognize
Adjusters use a recognizable playbook. The "friendly helper" approach builds rapport so you let your guard down. The "we just need to close the file" approach creates urgency. The "this will speed up your settlement" approach implies that cooperation is in your interest when it usually is not. The "your own policy requires this" approach may overstate the obligation. And the "why are you hiding something?" approach attempts to shame you into compliance.
None of these tactics change the underlying reality: a recorded statement is evidence, and evidence cuts both ways. The carrier will use your words to reduce what it pays. Recognizing the tactic is not about being hostile; it is about staying calm and keeping control of the conversation. You can always say, "I would like to think about that and get back to you," and then do exactly that.
When to Involve an Attorney
You should strongly consider speaking with an attorney before giving any recorded statement if you were injured, if liability is disputed, if there are multiple vehicles involved, if you have pre-existing medical conditions, or if the adjuster is pressing you to record immediately. These are exactly the situations where early words do the most damage.
An attorney can review your policy, explain your cooperation obligations, communicate with the adjuster on your behalf, and prepare you for any statement that is truly required. Many personal injury attorneys offer free consultations and handle cases on contingency, meaning you pay nothing upfront. For readers dealing with a car accident claim specifically, CarInjuryAccident connects injured people with experienced personal injury attorneys who can step in before the adjuster call does damage.
If you are unsure whether your situation warrants counsel, ask yourself three questions: Am I still treating for my injuries? Is there any dispute about who caused the crash? Has the adjuster asked for a recording more than once? A yes to any of these is a signal to get advice before you speak on the record.
Practical Checklist Before Any Adjuster Call
Preparation turns a stressful call into a controlled interaction. Keep this checklist nearby so you are not caught off guard.
- Confirm who is calling: name, company, and whether they represent your insurer or the other driver's insurer.
- Do not give a recorded statement on the first call; ask for the request in writing.
- Have your policy number, police report number, and medical provider information ready.
- Write down your questions and any details you are unsure about before the call.
- Keep a call log with dates, times, names, and a summary of what was discussed.
This checklist does two things. It slows the process down, which is almost always in your favor, and it creates a record. If the insurer later claims you were uncooperative, your log shows that you responded promptly and reasonably while protecting your rights. Documentation is quiet leverage.
Finally, remember that the adjuster works for the insurer, not for you. Their job is to resolve your claim for as little as possible. That does not make them evil; it makes them professionals with a different objective than yours. Treat the call as a business interaction, not a conversation with a friend. Be polite, be brief, and be careful. Protecting your claim when adjusters ask for a recorded statement is not about hiding anything. It is about making sure your words are accurate, complete, and given at a time when you actually understand your injuries, your policy, and your rights.