
How to Calculate Future Medical Expenses in a Settlement
Future medical expenses often decide your settlement's true value. Call 8332484565 for a free case evaluation and protect your long-term care.
By Celine Harrow
When a serious injury upends your life, the medical bills you have already paid are only part of the story. The bigger, harder question is what your care will cost in the months and years ahead. Future medical expenses often represent the largest single component of a personal injury settlement, yet they are also the easiest to underestimate. Insurance adjusters know this, and they routinely push claimants to accept lump sums that cover today's treatment but ignore tomorrow's surgeries, therapies, and prescriptions.
Understanding how to calculate future medical expenses settlement values is not about guessing. It is about building a documented, defensible projection based on your medical records, your doctor's prognosis, and verifiable cost data. Whether you are negotiating directly with an insurer or working with an attorney, the quality of your future care projection can mean the difference between a settlement that protects you and one that leaves you paying out of pocket for years.
Why Future Medical Costs Drive Settlement Value
A personal injury settlement is meant to make you whole, at least financially. That includes every reasonable medical expense you will need because of the injury, not just the bills already in your file. For catastrophic injuries such as traumatic brain injury, spinal cord damage, severe burns, or orthopedic trauma requiring multiple surgeries, future care can dwarf past treatment costs. Lifetime rehabilitation, assistive equipment, home modifications, and attendant care can run into the millions.
Even moderate injuries carry long tails. A knee injury that seems resolved may lead to arthritis and a joint replacement decades later. A back injury may require periodic injections, physical therapy, and pain management indefinitely. If your settlement does not account for these realities, you absorb the difference. That is why insurers fight so hard to keep future medical projections low, and why claimants need evidence rather than estimates.
The stakes are highest in mass tort and complex product liability cases, where injuries like hernias from mesh implants, cancers linked to contaminated water, or birth injuries from medications create decades of ongoing treatment needs. In these cases, projecting future care accurately is not optional; it is central to the claim. Platforms such as LegalCaseReview help injured people understand how litigation over these harms unfolds and why documented future damages matter so much.
The Core Formula Behind Future Medical Projections
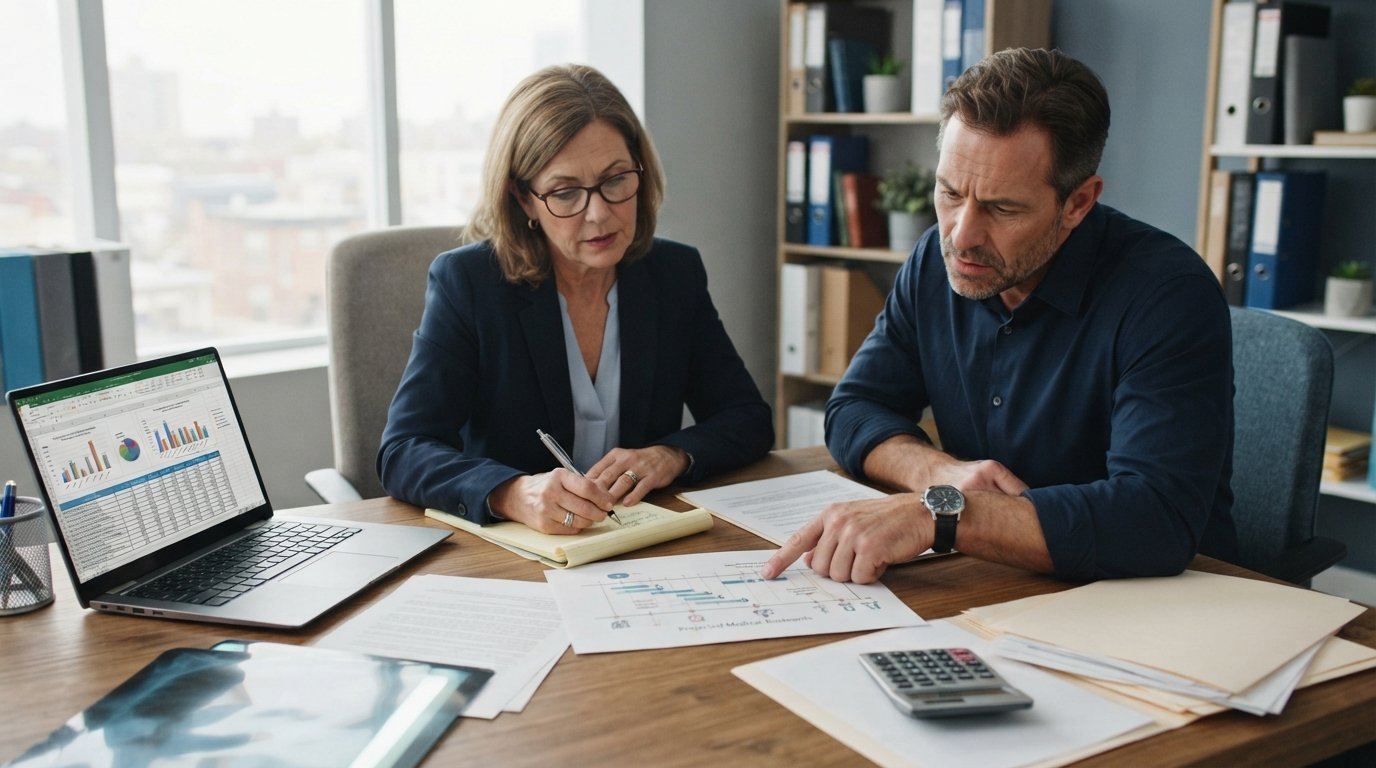
At its simplest, a future medical expense projection multiplies the annual cost of your ongoing care by the number of years you will need it, then adjusts for inflation and reduces the total to present value. Each step matters, and skipping any of them gives the insurer room to argue your number is inflated or speculative.
Here is the framework in plain terms:
- Identify every future care item. List each service, procedure, medication, device, and therapy your doctors expect you to need.
- Assign a current annual cost to each item. Use actual bills, provider fee schedules, or published cost data.
- Determine the duration of need. Some costs last a few years; others are lifelong.
- Apply a medical inflation rate. Healthcare costs typically rise faster than general inflation, often 3 to 5 percent per year.
- Discount to present value. Because a settlement pays you today for costs incurred later, the total is reduced using a conservative discount rate.
The result is a present-value figure that represents what the insurer should pay now to cover your future care. Courts and insurers expect this methodology, and a projection built this way is far harder to dismiss than a round number pulled from thin air. If you want a deeper walkthrough of the underlying math for injury claims, our guide on how to calculate future medical bills for a personal injury claim breaks down the calculations step by step.
Documents and Experts You Need
Numbers without evidence are just opinions. To make your projection credible, you need documentation that ties every dollar to a medical necessity. The foundation is your treatment records, but the key document is a life care plan or a narrative report from a treating physician or medical expert that explains what care you will need, how often, and for how long.
A life care plan is prepared by a qualified professional, often a nurse life care planner or rehabilitation specialist, who reviews your records and builds an itemized schedule of future needs with costs attached. It covers everything from routine follow-up visits to surgical revisions, durable medical equipment, prescription medications, psychological counseling, and home health aides. For catastrophic injuries, an economist may then take that plan and convert it into a present-value figure using accepted financial methods.
Gather and organize the following before you or your attorney begin negotiating:
- Complete medical records, including imaging, operative reports, and discharge summaries
- Written prognosis from your treating physicians describing expected future care
- A life care plan or itemized future needs assessment
- Pharmacy records and prescription cost documentation
- Bills and explanation of benefits forms showing what insurers have paid and what you owe
If your injury is part of a mass tort or product liability matter, the litigation may already have expert reports and settlement grids that inform future damage calculations. In those situations, an experienced attorney can match your specific medical profile to the categories of compensation the case recognizes. Reviewing how similar claims have been valued can also anchor your expectations, which is where a service like FreeLegalCaseReview.com can connect you with attorneys who handle these complex matters.
Common Mistakes That Shrink Future Medical Awards
Even claimants with strong medical evidence sometimes see their future care numbers slashed. The problem is usually procedural rather than medical. Insurers exploit gaps in documentation, unrealistic assumptions, and vague testimony. Knowing the pitfalls in advance helps you avoid them.
One frequent error is treating future care as a single lump sum with no itemization. Adjusters love a vague number because they can counter with an even vaguer, lower one. Another is ignoring the cost of medications and routine maintenance care, which accumulate significantly over decades. Claimants also often fail to account for the possibility of complications, revision surgeries, or the accelerated wear and tear that an injury places on other parts of the body.
Another mistake is accepting the insurer's present-value discount rate without scrutiny. A high discount rate shrinks your award significantly. A defensible projection uses a conservative rate consistent with safe investments, and your attorney should be prepared to justify it. Finally, many claimants settle before their condition has stabilized. Without a clear prognosis, you cannot know what future care you will need, and settling too early risks waiving compensation for complications that have not yet appeared.
How Attorneys and Insurers Value Your Claim Differently
Insurers approach future medical expenses with a bias toward closure. Their models often assume you will improve, stop treatment sooner than your doctors predict, or simply not pursue care. They may use outdated cost data or apply aggressive discount rates. Their goal is a number that looks reasonable on paper but does not reflect what treatment actually costs in your community.
Attorneys build projections from the ground up, using your specific providers, your specific prognosis, and verifiable cost sources. They also account for non-medical consequences that flow from future care needs, such as lost earning capacity if you cannot work, transportation costs for ongoing appointments, and the value of unpaid family caregiving. These elements are recoverable in many jurisdictions but are easy to overlook without experienced guidance.
The gap between the two approaches is why negotiation often centers on methodology rather than facts. If your projection is well documented, the insurer must either accept it or explain why its alternative is more reliable. That pressure is what moves settlement offers upward. When the numbers are supported by a life care plan, physician testimony, and a credible economist, insurers face a real risk that a jury will award the higher figure, and they adjust accordingly.
When to Get a Free Case Evaluation
Calculating future medical expenses is technical work, and doing it well usually requires professional help. If you are handling a claim involving ongoing treatment, a permanent injury, or a condition that may worsen, a free case evaluation is the practical next step. It costs nothing, carries no obligation, and gives you a realistic picture of what your future care is worth before you sign anything.
During an evaluation, an attorney or intake specialist will review your medical records, ask about your prognosis, and explain how future damages are typically calculated in cases like yours. If your injury involves a mass tort, such as exposure to a dangerous drug or defective medical device, the evaluation will also assess whether you qualify for an existing litigation. This early clarity helps you avoid the most expensive mistake in injury claims: accepting a settlement that covers today but not tomorrow.
Take the time to document your care, consult qualified professionals, and insist on a projection built from evidence. Your future health depends on it, and so does the fairness of your settlement.