
Catastrophic Injury Claim: Long Term Care Compensation
Secure lifetime care costs in a catastrophic injury claim. Call (833)-248-4565 for a free case evaluation and protect your family's future.
By Max Thompson
A spinal cord injury at 24 can mean seven decades of personal care, home modifications, and lost income. A traumatic brain injury in a child can require round the clock supervision for life. When a family faces these realities, the financial question is not about a single hospital bill but about whether a settlement will still be adequate twenty or forty years from now. That is the core challenge of a catastrophic injury claim long term care compensation: translating a lifetime of future needs into a present day dollar figure that insurers will actually fund. This article explains how those claims are built, how life care plans quantify the unthinkable, and what families can do to protect a severely injured loved one from a lifetime of financial shortfall.
What Makes an Injury Catastrophic and Why Long Term Care Changes Everything
Not every serious injury is catastrophic in the legal sense. Insurance companies and courts typically reserve that label for conditions that permanently alter a person's ability to live independently, work, or care for themselves. The most common categories include traumatic brain injury (TBI), spinal cord injury (paraplegia and quadriplegia), amputation, and severe burns. What unites them is not the initial trauma but the decades of medical, functional, and financial consequences that follow.
Consider the difference between a broken leg and a spinal cord injury at the T4 level. The broken leg heals, and the claim is largely about a few months of lost wages and medical bills. The spinal cord injury does not heal. It may require wheelchair accessible housing, a modified vehicle, daily assistance with bowel and bladder management, pressure sore prevention, and regular physical therapy. None of those costs stop after the settlement check clears. A catastrophic injury claim long term care compensation must capture that ongoing reality, or the money will run out long before the need does.
Families often underestimate how quickly care costs accumulate. A single hour of home health aide support can cost $25 to $35, and a person with a high level spinal cord injury may need eight or more hours per day. That is roughly $73,000 to $102,000 per year before factoring in medical equipment, therapy, and home modifications. Over thirty years, the total can exceed $2 million. A settlement that ignores long term care is not a settlement at all; it is a temporary patch on a permanent problem.
Life Care Plans: The Financial Blueprint for Lifetime Needs
How do you put a price on a lifetime of care? The answer is a life care plan, a detailed document prepared by a certified life care planner, often a nurse or rehabilitation specialist with training in cost analysis. This plan becomes the evidentiary backbone of a catastrophic injury claim long term care compensation demand. It itemizes every anticipated medical and functional need, assigns a frequency (daily, weekly, annual), and projects costs over the injured person's expected lifespan.
A well constructed life care plan typically includes several categories of expense. The following list shows the most common items:
- Medical care: physician visits, specialist consultations, hospitalizations, medications, and surgical procedures related to the injury.
- Rehabilitation and therapy: physical, occupational, speech, and cognitive therapy, often at a defined frequency for life.
- Attendant care: home health aides, nursing services, and supervision for individuals who cannot be left alone.
- Equipment and supplies: wheelchairs, ventilators, catheters, pressure relief cushions, and replacement schedules for each item.
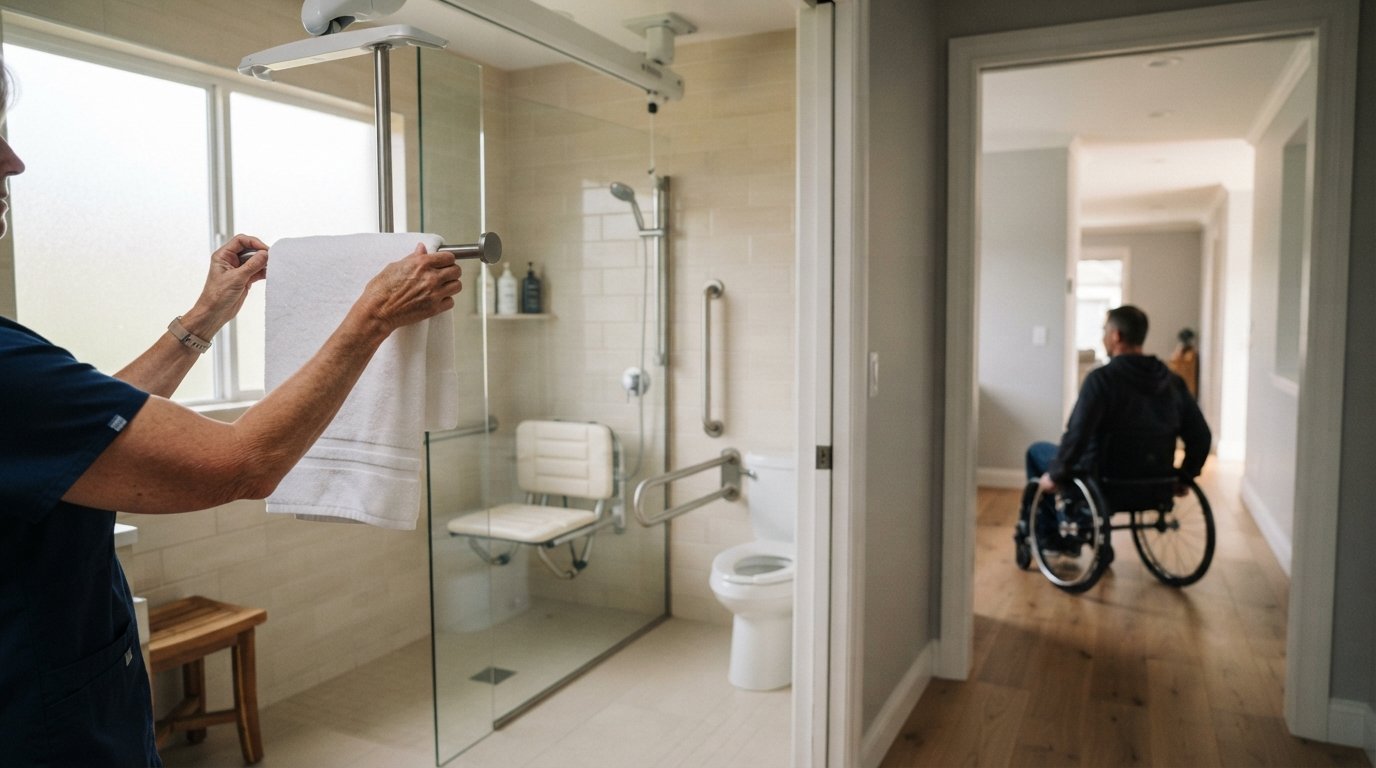
- Home and vehicle modifications: ramps, widened doorways, roll in showers, accessible vans, and the cost of future relocation if needed.
Each of those categories is priced using current market rates and then projected forward with medical inflation, which historically runs higher than general inflation. A life care planner will also account for the injured person's life expectancy, which may be reduced by the injury itself. For a young victim, the plan might cover fifty or sixty years, turning what looks like a modest annual cost into a multi million dollar total. Without such a plan, a family negotiating with an insurer is essentially guessing, and insurers are trained to exploit guesses.
It is important to understand that a life care plan is not a wish list. Defense attorneys will scrutinize it, and a poorly supported plan can be attacked as speculative. That is why experienced legal teams work with planners who can defend each line item with medical literature, physician recommendations, and cost data. If you are exploring your options, a guide on injury claim help in Salt Lake City can show how local claims are built, though the principles apply nationwide.
Lost Earning Capacity: The Decades Long Income Gap
Long term care is only half of the compensation equation. The other half is what the injured person would have earned if the injury had not occurred. For a young victim, that lost earning capacity can dwarf the medical costs. A 25 year old construction worker with a high school education who becomes quadriplegic may have been on track to earn $50,000 per year with overtime, plus benefits. Over a 40 year work life, with raises and inflation, the present value of that lost income can exceed $1.5 million. A 10 year old with a TBI may never enter the workforce at all, and the loss is calculated over an even longer horizon.
Proving lost earning capacity requires more than a pay stub. Economists and vocational experts analyze the injured person's age, education, work history, and career trajectory, then compare that to post injury earning capacity. For children, they may use statistical averages or parental income as a proxy. The defense will argue that the victim could have worked in a sedentary job, or that the injury did not affect earning potential. A strong claim anticipates those arguments with expert testimony and detailed documentation.
What many families do not realize is that lost earning capacity is not limited to wages. It includes fringe benefits, retirement contributions, and the value of household services the injured person can no longer perform, such as home maintenance and childcare. Those services have a market value, and a life care plan or economic report can quantify them. When added to long term care costs, the total claim can easily reach seven or eight figures, which is why insurers fight so hard to minimize both categories.
Building a Catastrophic Injury Claim That Funds a Lifetime
Securing meaningful long term care compensation is not a matter of asking for a big number. It is a matter of building a claim that an insurer or jury cannot easily dismiss. That process begins immediately after the injury, often while the family is still processing the trauma. Evidence preservation is time sensitive: surveillance video, vehicle data, witness statements, and employment records can disappear or degrade. An experienced legal team will send spoliation letters and begin gathering records before the insurance company even assigns a claim number.
The next step is assembling the right experts. A catastrophic injury claim long term care compensation package typically relies on a neurologist or orthopedic surgeon to establish the severity and permanence of the injury, a life care planner to quantify future needs, an economist to calculate present value and lost earnings, and sometimes a vocational rehabilitation expert to assess employability. Each expert produces a report that becomes part of the demand package. Insurers know that a well documented demand is harder to lowball, and they often increase their reserves when they see credible expert support.
Families should also be prepared for the litigation timeline. Catastrophic claims rarely settle quickly because the stakes are high and the future is uncertain. It may take a year or more to stabilize the injured person's condition enough for a life care plan to be reliable. During that time, the legal team may need to secure interim funding for medical care, either through the victim's own insurance (such as medical payments coverage or health insurance) or through a lawsuit funding arrangement. Understanding those options early can prevent a financial crisis while the claim develops.
When it comes time to negotiate, the demand package does the heavy lifting. It tells a story: this is who the person was, this is what happened, this is what they need for the rest of their life, and this is what it costs. A skilled attorney will walk the adjuster through the life care plan line by line, emphasizing the non negotiable nature of attendant care and medical equipment. If the insurer refuses to fund long term care adequately, the case may go to trial, where a jury is often more sympathetic to a severely injured victim than a corporate adjuster is.
Common Pitfalls That Undermine Long Term Care Compensation
Even strong claims can be weakened by avoidable mistakes. One of the most common is accepting an early settlement before the full extent of the injury is known. A person with a TBI may seem to be recovering in the first few months, only to plateau or decline later. Once a release is signed, the claim is over, and additional care is the family's financial responsibility. Attorneys who handle catastrophic cases typically advise against any settlement until a life care plan is complete and the injured person's condition has stabilized.
Another pitfall is failing to document the day to day reality of caregiving. Insurers rely on medical records, but those records often do not capture the hours a family member spends bathing, feeding, and supervising the injured person. A caregiver log, even a simple notebook, can be powerful evidence of the true cost of care. Similarly, photographs and video of home modifications, therapy sessions, and adaptive equipment help humanize the claim and justify the expenses.
Families should also be cautious about social media. Defense attorneys routinely search for posts that suggest the victim is more capable than claimed. A photo of a person with a spinal cord injury smiling at a family event can be taken out of context to argue that they are not suffering. The safest approach is to avoid posting about the injury or the claim entirely until the case is resolved.
Finally, choosing the right attorney matters more than most families realize. Catastrophic injury claims require resources: expert fees, investigation costs, and the ability to front expenses for years. A firm that handles mostly fender benders may not have the infrastructure to pursue a lifetime care claim. When evaluating representation, ask about their experience with life care planners, their access to economic experts, and their willingness to take the case to trial if needed. For those considering a broader range of legal challenges, platforms like CarInjuryAccident connect individuals with attorneys in personal injury and related practice areas, which can be a useful starting point for comparing options.
Steps Families Can Take Right Now
If a loved one has suffered a catastrophic injury, the path forward can feel overwhelming. The following numbered steps can help organize the process and protect the claim:
- Secure immediate medical care and follow all recommendations. Gaps in treatment are used by insurers to argue that the injury is less severe than claimed.
- Document everything. Keep a calendar of medical appointments, a caregiver log, receipts for equipment and modifications, and a journal of how the injury affects daily life.
- Do not speak to the insurance adjuster without legal guidance. Adjusters are trained to elicit statements that can later be used to reduce the claim.
- Consult a catastrophic injury attorney as soon as possible. Early involvement preserves evidence and ensures the claim is built correctly from the start.
- Ask about a life care plan. If the attorney does not mention it, bring it up. A claim without a life care plan is unlikely to capture long term care costs.
Those steps are not a substitute for legal advice, but they can help a family avoid the most damaging early mistakes. The sooner a qualified team is in place, the sooner the work of quantifying a lifetime of care can begin.
Why Insurers Resist Long Term Care Claims and How to Respond
Insurance companies are in the business of paying as little as possible. Long term care compensation is expensive, so insurers deploy a range of tactics to reduce or deny it. They may argue that the injured person will improve beyond current expectations, that family members will provide care for free, or that a cheaper alternative (such as a group home instead of in home care) is appropriate. They may also dispute life expectancy, claiming the victim's lifespan is shorter than the life care plan assumes, which would reduce the total cost.
Each of those arguments can be countered with evidence. Treating physicians can testify about the permanence of the injury. A life care planner can explain why family care is not a substitute for professional care and why the recommended services are medically necessary. An economist can defend the present value calculation. And if the insurer persists in undervaluing the claim, the threat of trial and a potential verdict that includes pain and suffering can change the calculus. Juries in catastrophic injury cases often award far more than insurers offer during negotiation, which is why a well prepared case has leverage.
It is also worth noting that many catastrophic injury claims involve multiple sources of compensation. Health insurance, medical payments coverage, underinsured motorist coverage, and workers' compensation may all apply. An attorney can coordinate those benefits to avoid liens and ensure the victim receives the full amount available. Failing to identify all sources can leave money on the table, and in a lifetime care claim, even a small percentage can mean hundreds of thousands of dollars.
For families navigating this process, the most important takeaway is that long term care compensation is not automatic. It must be demanded, documented, and defended. The difference between a settlement that funds a lifetime of care and one that runs out in five years often comes down to the quality of the legal team and the thoroughness of the evidence. Taking the time to build the claim correctly is an investment in the injured person's future.
If you are facing a catastrophic injury claim and wondering how to secure long term care compensation, start by requesting a free case evaluation. A confidential review can clarify your options, connect you with experienced attorneys, and help you understand what a lifetime of care actually costs. The earlier you act, the more evidence you can preserve and the stronger your claim will be.