
Can You Claim Lost Earning Capacity After an Injury?
Injured and facing a reduced career? Learn if you can claim lost earning capacity after an injury. Call (833)-248-4565 for a free case evaluation.
By Evander Shaw
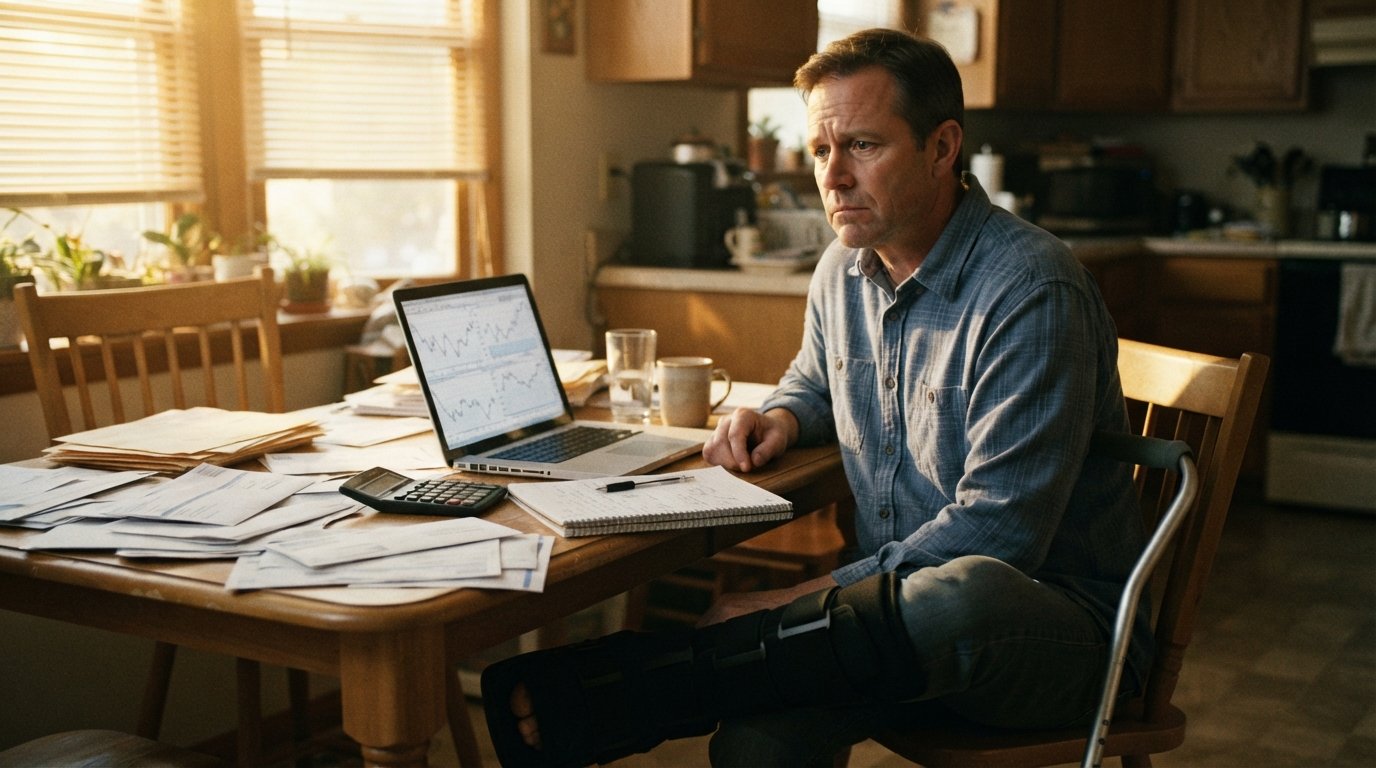
You did everything right. You went to work, followed the safety rules, and built a career. Then an injury changed everything. The medical bills are one thing, but the nagging question is often bigger: what happens to the money you would have earned in the years ahead if you can no longer do the work you once did? That question sits at the heart of a legal concept called lost earning capacity, and it is one of the most misunderstood parts of a personal injury claim. Understanding how it works, what evidence proves it, and how insurers try to minimize it can mean the difference between a settlement that protects your future and one that leaves you short when your injuries catch up with your career.
This guide breaks down the difference between documented lost wages and diminished earning capacity, explains how economists and vocational experts put a dollar figure on future losses, and shows how factors like age, education, and permanent restrictions shape that number. It also explains why a free case evaluation with a qualified attorney is often the fastest way to understand whether your claim is strong enough to pursue. If you are considering your options, a no-obligation case review can help you see the full picture before you sign anything with an insurance company.
Lost Wages vs. Lost Earning Capacity: What Is the Difference?
Lost wages are the easy part of a claim, at least in theory. These are the paychecks you missed because you were recovering from your injury. If you have pay stubs, time records, and a doctor's note taking you off work, you can document the exact amount you lost. Insurance adjusters understand this calculation because it is concrete. They may argue about the number of days, but they cannot dispute the basic math. Lost earning capacity is different. It is not about the paychecks you already missed. It is about the income you will never be able to earn in the future because your injury has reduced your ability to work at the same level.
Think of it this way. A construction foreman who suffers a back injury may return to a desk job, but if he can no longer supervise job sites, climb ladders, or work the hours he once did, his future earning potential is permanently diminished. Even if he is working today, the gap between what he would have earned over a career and what he can now earn is a compensable loss. The same principle applies to a nurse with a shoulder injury who cannot lift patients, a truck driver with a neck injury who cannot sit for long hauls, or an office manager with a cognitive injury who cannot manage the same workload. Lost earning capacity captures the long-term reduction in your ability to generate income, whether or not you have already returned to some form of employment.
This distinction matters because insurers often try to close a claim by pointing to a return to work. They will argue that because you are earning a paycheck, you have no future loss. That argument fails when your new job pays less, offers fewer hours, or lacks the advancement opportunities you had before. Proving diminished earning capacity requires a forward-looking analysis, and that is where the evidence gets more complex.
How Earning Capacity Is Valued: The Experts Behind the Number
Because lost earning capacity is about the future, it cannot be proven with a simple receipt. Instead, attorneys rely on a combination of vocational and economic experts to build a reliable estimate. A vocational expert assesses your physical and cognitive restrictions, reviews your work history, and determines what kinds of jobs you can realistically perform now. They may use labor market data to show whether those jobs exist in your area, how many hours they offer, and what they pay. An economist then takes that vocational assessment and translates it into a dollar figure, accounting for factors like wage growth, benefits, and the probability that you would have remained employed over time.
The evidence these experts rely on typically includes a mix of medical and employment records. A strong claim usually includes the following pieces of proof:
- Medical records and treating physician opinions that document permanent restrictions, such as lifting limits, sit/stand requirements, or cognitive deficits.
- Vocational expert reports that identify the gap between your pre-injury career trajectory and your post-injury earning capacity.
- Economic reports that calculate present value, accounting for inflation, discount rates, and work-life expectancy.
- Employment records, including pay stubs, tax returns, performance reviews, and promotion history, to establish your baseline earnings and future potential.
- Testimony from former supervisors or coworkers about your skills, reliability, and likelihood of advancement.
Each of these pieces serves a purpose. The medical records establish the foundation: without a permanent restriction, there is no diminished capacity. The vocational expert connects that restriction to the real-world job market. The economist converts that connection into a number a jury or adjuster can understand. When these elements line up, an insurer has a much harder time arguing that your future losses are speculative. When they are missing, the claim becomes vulnerable to low-ball offers. This is why building a complete evidentiary record early is so important.
Age, Education, and Prior Earnings: How They Shape Your Claim
No two diminished earning capacity claims look alike because the calculation depends heavily on who you are and what your career looked like before the injury. Age is one of the most significant factors. A younger worker generally has more years of future earnings ahead, which can make the total loss larger even if the annual gap is modest. An older worker closer to retirement may have a smaller overall loss, but the claim can still be substantial if the injury eliminates the final high-earning years of a career. Insurers and economists use work-life expectancy tables to estimate how many years of lost income are reasonable to include.
Education and training also play a role. A worker with specialized skills or advanced degrees may have a steeper earnings trajectory, which means a greater loss when that trajectory is cut short. On the other hand, a worker with limited education may have fewer transferable skills, making it harder to find alternative employment within their restrictions. Both scenarios can support a strong claim, but they require different types of evidence. Prior earnings establish the baseline. If you were earning $80,000 per year with regular raises and overtime, that history supports a higher future loss than a steady $40,000 salary with no growth. Tax returns, W-2s, and pay stubs from the years before the injury are essential for showing the adjuster or jury what you were actually earning and what you were likely to earn.
These factors interact in ways that are not always obvious. A 55-year-old electrician with a high school diploma and decades of specialized experience may have a stronger claim than a 30-year-old office worker with a college degree, depending on the severity of restrictions and the availability of alternative work. This is why a one-size-fits-all formula does not work. An experienced attorney will look at your specific combination of age, education, work history, and medical restrictions to build a valuation that reflects your actual circumstances.
Permanent Restrictions and Their Impact on Future Employment
A permanent restriction is the anchor of a lost earning capacity claim. Without it, the argument collapses into speculation. A restriction can be obvious, such as the loss of a limb or a spinal fusion that prevents heavy lifting. It can also be less visible, such as chronic pain that limits sitting tolerance, a traumatic brain injury that affects concentration, or a psychological condition that makes high-stress work untenable. Treating physicians document these restrictions in the form of work status notes, functional capacity evaluations, and narrative reports. The more specific and well-supported the restriction, the stronger the claim.
The impact of a restriction depends on the labor market. A restriction that prevents overhead lifting may have little effect on an accountant but catastrophic consequences for a warehouse worker. Vocational experts analyze this by comparing the physical demands of your past work with the demands of jobs you could now perform. They also consider whether those alternative jobs pay comparable wages, offer full-time hours, and provide benefits. In many cases, the alternative jobs pay significantly less, and that wage gap becomes the measure of your diminished capacity. If no alternative jobs exist within your restrictions, the claim may be even larger because it reflects a total loss of earning capacity.
Insurers frequently challenge permanent restrictions by sending claimants to independent medical examinations. These exams are rarely independent in practice, and the resulting reports often downplay the severity of restrictions. Having your own treating physician's documentation, along with a vocational expert who can rebut the insurer's narrative, is critical. For readers dealing with less dramatic collisions, our guide on whether you can claim injury after a low speed crash explains why even minor impacts can produce lasting limitations that affect earning capacity.
Why a Free Case Evaluation Can Gauge Claim Strength
Lost earning capacity claims are among the most complex in personal injury law because they require experts, documentation, and a clear theory of how the injury changes your future. Many injured workers do not realize they have this claim until an attorney reviews their situation. A free case evaluation provides an opportunity to sit down with a legal professional, explain your injury and work history, and get an honest assessment of whether diminished earning capacity is a viable part of your case. These evaluations are typically confidential and carry no obligation to hire the attorney afterward.
During an evaluation, an attorney will typically ask about your medical treatment, your job duties before and after the injury, your earnings history, and any restrictions your doctors have imposed. They may also ask whether you have applied for other jobs or been turned down because of your limitations. From there, they can outline the types of evidence they would need to build a claim and give you a sense of the range of outcomes. For many people, this conversation is the first time they understand that their future losses may be compensable. Platforms like LawyerOffer connect injured individuals with attorneys who handle these claims and can provide that kind of preliminary review.
It is important to remember that an insurance adjuster's job is to settle your claim for as little as possible. They are not on your side, and they are not looking out for your future earning potential. Having an attorney review your case before you accept a settlement can prevent you from signing away rights you did not know you had. If you are unsure whether your injury has affected your long-term earning capacity, a free case evaluation is a low-risk way to find out.
Steps to Strengthen a Lost Earning Capacity Claim
If you believe your injury has reduced your future earning potential, the actions you take in the weeks and months after the injury can significantly affect the strength of your claim. The process is not complicated, but it requires consistency and attention to detail. The following steps can help preserve the evidence you will need:
- Follow your doctor's treatment plan and report all symptoms, including pain, fatigue, and cognitive difficulties, so they are documented in your medical records.
- Ask your treating physician for a written opinion about permanent restrictions and how those restrictions affect your ability to perform your past job duties.
- Keep copies of pay stubs, tax returns, performance reviews, and any records showing raises, promotions, or overtime you regularly worked before the injury.
- Document any attempts to return to work, including reduced hours, lower pay, or accommodations your employer had to make.
- Consult with an attorney before speaking to an insurance adjuster about future losses or signing any release.
These steps create a paper trail that supports both the medical and vocational sides of the claim. They also make it harder for an insurer to argue that your limitations are exaggerated or that your future losses are speculative. The earlier you start, the more complete your record will be when it comes time to negotiate or file a lawsuit.
Lost earning capacity is not a theoretical concept. It is a real, measurable loss that affects real families for years after an injury. Whether you are a young worker at the start of a career or an experienced professional nearing retirement, the law recognizes that an injury can steal more than your health. It can steal your future income. Understanding the difference between lost wages and diminished capacity, gathering the right evidence, and getting a professional assessment of your claim are the keys to protecting what you have earned and what you stand to earn. If you have questions about your situation, a free, confidential case evaluation is a sensible next step.