
Can Insurance Use Your Social Media Against Your Injury Claim?
Can insurance company use my social media against my injury claim? Yes, and your posts can reduce your payout. Call (833)-248-4565 for a free case evaluation.
By Zaria Penrose
You post a photo of your daughter's birthday party, a check-in at your favorite restaurant, or a quick update about a weekend hike. Weeks later, an insurance adjuster cites that post as proof your injury is not as serious as you claim. This scenario is not hypothetical. It plays out in personal injury cases across the country every day, and it is one of the most common ways claimants unintentionally damage their own recovery. If you are wondering can insurance company use my social media against my injury claim, the short answer is yes, and the longer answer explains exactly how they do it, what they look for, and how you can protect yourself while your case is open.
Insurance companies have entire investigative teams dedicated to monitoring claimants online. They review public posts, analyze timestamps, compare photos against medical records, and look for any inconsistency they can use to reduce or deny a payout. Understanding their tactics is the first step toward protecting your claim. The second step is knowing what to post, what to avoid, and when to change your privacy settings. This article walks through all of it, from how adjusters mine your profiles to what happens if your private content becomes part of a discovery request.
How Insurance Investigators and Adjusters Mine Your Social Media
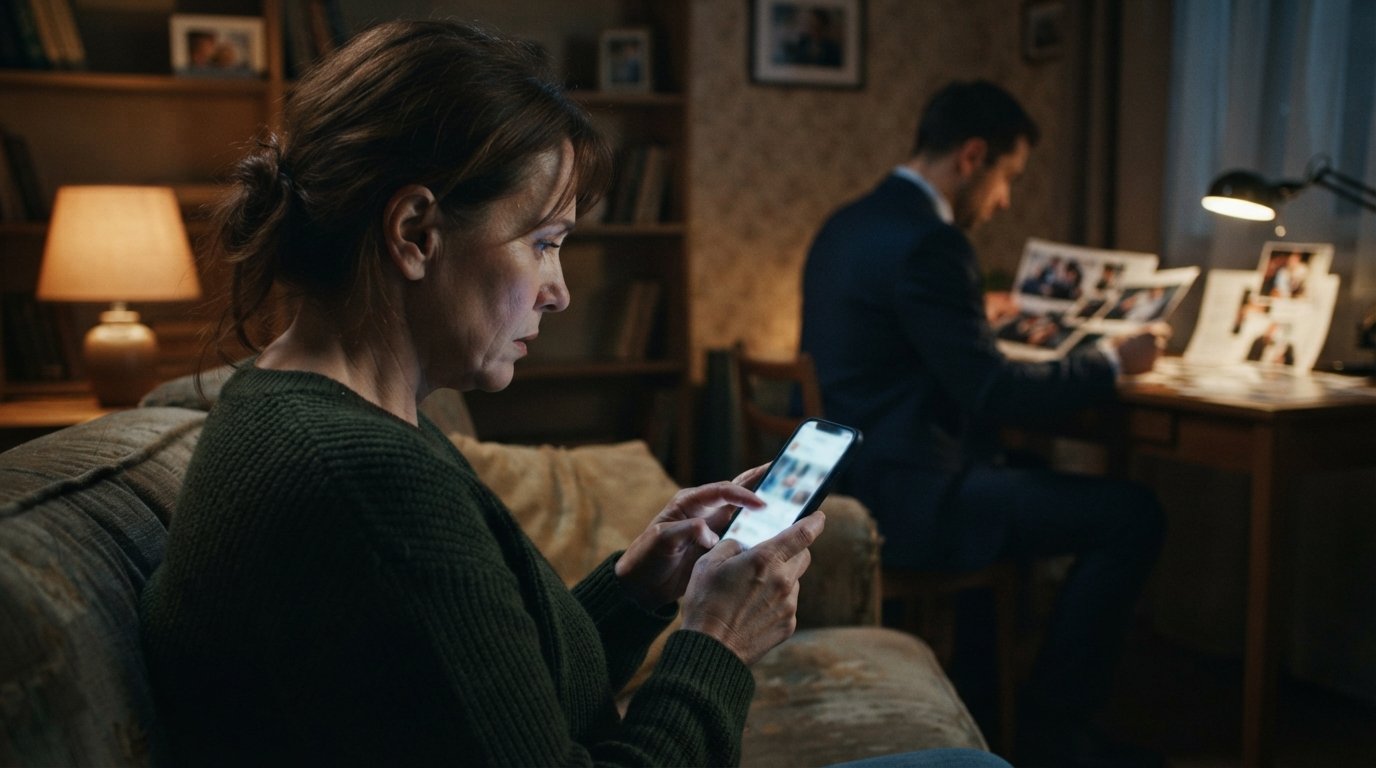
Insurance adjusters do not rely on guesswork. They use structured investigative methods to examine your online presence, and they often document everything they find. The process typically begins the moment you file a claim or even earlier, when the insurer first learns about your injury. Adjusters and defense investigators search your name across major platforms, review public posts, and save screenshots for later use. They may also look at friends' profiles, tagged photos, and public comments you have made on other people's posts.
What makes this surveillance powerful is the paper trail. A photo timestamped two weeks after your accident showing you lifting a cooler or dancing at a wedding can directly contradict a medical record describing severe back pain. An adjuster will not need to prove the photo is recent beyond a reasonable doubt; they only need to raise doubt about your credibility. That doubt becomes leverage in settlement negotiations. For a deeper look at how to manage the early stages of a claim, including choosing the right attorney, see this guide on a free injury consultation in Worcester, Massachusetts.
Adjusters also look for patterns of statements, not just isolated posts. If you post frequently about your active lifestyle before the accident and then go silent for weeks, they may notice. More importantly, if you resume posting about physical activities while your claim says you are bedridden, they will absolutely notice. The goal for the insurer is not to catch you in a lie; it is to find any inconsistency that a jury might interpret as exaggeration or fraud. Even innocent posts can be twisted to serve that purpose.
Here are the specific types of online activity that insurance investigators commonly review:
- Photos and videos showing physical activity, such as hiking, sports, lifting, or dancing
- Check-ins at gyms, amusement parks, vacation destinations, or other locations that suggest mobility
- Posts about work, side projects, or volunteer activities that could suggest you are not as limited as claimed
- Comments and replies where you describe your pain level, recovery progress, or daily routine
- Tagged photos on friends' pages that you may not have approved but are still visible to the public
The last item on that list is especially important. You might think your own profile is locked down, but a friend's public post that tags you can still be seen by anyone. Investigators know this and routinely check the profiles of claimants' friends and family members. The lesson is that your online footprint extends beyond your own accounts, and anything visible to the public is fair game for an adjuster building a case against your claim.
Common Post Types That Undermine Injury Claims
Most claimants do not set out to damage their own cases. They post about their lives because that is what people do, and they do not realize that a single photo can shift the trajectory of a settlement. The following post types are the most frequent culprits in injury cases, and each one carries a specific risk. Understanding these risks helps you avoid the most common mistakes.
Vacation and travel photos. A picture of you on a beach might seem harmless, but if your claim describes limited mobility or severe pain, an adjuster will use that image to argue you are more active than you claim. Even a photo of you sitting on a plane can raise questions about your ability to tolerate prolonged sitting, which is often a key factor in back and neck injury claims. The insurer does not need to prove you were swimming or running; the mere suggestion of travel can cast doubt on your reported limitations.
Gym and fitness check-ins. Fitness-related posts are among the most damaging. An adjuster who sees a check-in at a gym or a photo of you holding weights will argue that your injury cannot be as severe as you stated. Even if you were only walking on a treadmill for physical therapy, the visual of a gym setting can be misrepresented in a settlement negotiation. The same logic applies to photos from yoga classes, hiking trails, or sports events.
Home improvement and yard work. Posts about painting a room, building a deck, or landscaping your yard can be used to suggest you are capable of physical labor. If your claim includes lost wages or an inability to perform household tasks, these posts directly undercut that argument. Adjusters love these photos because they create a clear contrast with medical records that describe pain with bending, lifting, or prolonged standing.
Social gatherings and events. Photos from parties, weddings, or concerts are frequently used against claimants. An adjuster might argue that if you can attend a loud, crowded event, you cannot be suffering from severe headaches, anxiety, or fatigue. The context of the photo does not matter to the insurer; what matters is the impression it creates. A single smiling photo at a family gathering can be framed as evidence that your pain is not as disruptive as you claim.
Posts about work or income. Statements about side jobs, freelance projects, or new business ventures can be used to challenge lost wage claims. If you claim you cannot work but post about a new consulting gig or a craft business, the insurer will question your credibility. Even casual comments like "excited to start my new project" can be screenshotted and used in negotiations. The safest approach is to avoid discussing work or income online while your claim is open.
Do Privacy Settings or Deleting Posts Actually Protect You?
Many claimants believe that setting their profiles to private or deleting old posts will solve the problem. The reality is more complicated. Privacy settings do reduce the risk of casual surveillance, but they do not make you invisible. Insurance investigators can still view public portions of your profile, and they can often find your content through friends' accounts, tagged photos, or cached versions of pages. More importantly, privacy settings do not prevent your content from being requested during litigation.
Deleting posts is also not a reliable solution. In some cases, deleting content after a claim is filed can be viewed as spoliation of evidence, which is a legal term for destroying evidence that may be relevant to a case. If a court determines that you deleted posts that could have been relevant, you could face sanctions or an adverse inference, meaning the court may assume the deleted content was unfavorable to you. This is a serious risk that many claimants do not consider. Instead of deleting posts, the better approach is to stop posting about your case and consult an attorney before making any changes to your online presence.
Privacy settings can help in one specific way: they limit what casual observers can see without a formal request. If your account is private and an adjuster cannot view your content, they may need to obtain it through discovery, which is a more formal process. That process takes time and resources, and some insurers may decide it is not worth pursuing for a smaller claim. However, for larger claims, the insurer may still push for access. The key takeaway is that privacy settings are a helpful layer of protection but not a guarantee. You should assume that anything you post, even privately, could eventually become part of your case.
Here are practical steps to consider if you want to reduce your online exposure while a claim is open:
- Set your accounts to private and review your friend list to remove anyone you do not know or trust.
- Ask friends and family not to tag you in posts or share your location without your permission.
- Stop posting about your injury, your recovery, your activities, or your case entirely.
- Avoid deleting old posts without legal advice, as deletion can create more problems than it solves.
- Consult your attorney before making any significant changes to your social media accounts after filing a claim.
These steps are not a substitute for legal advice, but they can help you avoid the most common pitfalls. The most important rule is to assume that anything you post could be seen by the insurance company, even if your account is private. That mindset will help you make better decisions about what to share online.
How Discovery Requests Can Reach Private Content in Litigation
If your injury claim turns into a lawsuit, the discovery process gives the other side broad powers to request evidence. Discovery is the formal process by which parties exchange information before trial, and it can include requests for documents, written interrogatories, and depositions. Social media content is increasingly included in these requests. An insurer can ask you to produce posts, messages, photos, and even metadata from your accounts if they can show the content is relevant to your claim.
Courts have generally held that social media content is discoverable if it is relevant and not protected by privilege. If you claim that your injury prevents you from engaging in certain activities, the court may allow the insurer to request content that could show otherwise. This can include private posts, direct messages, and even deleted content that can be recovered through forensic tools. The scope of discovery is not unlimited, but it is broader than most claimants expect. An experienced attorney can help you respond to these requests properly and protect your rights.
For claimants who are considering legal representation, it is worth understanding how the attorney selection process works. A service like CheapInjuryLawyer offers a free case review and can connect you with participating personal injury attorneys, many of whom work on contingency. This can be a useful resource for understanding your options without upfront cost. When choosing an attorney, ask specifically about their experience with social media evidence and discovery requests. An attorney who understands the digital landscape can help you avoid mistakes and respond to discovery requests strategically.
It is also important to understand that you have obligations during discovery. You cannot simply ignore a request or delete content after receiving it. Doing so can lead to sanctions, adverse inferences, or even dismissal of your case. The safest approach is to preserve all relevant content and let your attorney guide you through the process. If you have not yet hired an attorney, this is one of the most important reasons to do so before your case reaches the litigation stage.
Practical Posting Rules to Follow While Your Claim Is Open
The simplest and most effective way to protect your claim is to change your social media habits while your case is active. You do not need to disappear from the internet entirely, but you should treat every post as if the insurance adjuster is reading it. The following rules are designed to help you avoid the most common mistakes without giving up your online life completely.
Rule 1: Do not post about your injury or your case. This includes updates about doctor visits, pain levels, recovery progress, and settlement negotiations. Anything you say about your injury can be used to contradict your medical records or your testimony. Even positive updates like "feeling better today" can be taken out of context and used to argue that your injury was not serious.
Rule 2: Avoid posting photos or videos of physical activity. This is the single most common mistake claimants make. If you are physically capable of hiking, lifting, playing sports, or doing yard work, those images can be used to argue that your injury does not limit your daily life as much as you claim. Even if the activity was a one-time event or a doctor-approved therapy, the insurer will not care about the context.
Rule 3: Do not check in at locations that suggest mobility. Check-ins at gyms, amusement parks, sporting events, or vacation destinations can be used to argue that you are more active than your claim suggests. If you must post, avoid location tags and check-ins entirely. The same applies to posts that reveal your location indirectly, such as photos with recognizable landmarks.
Rule 4: Do not discuss work, income, or side projects. If your claim includes lost wages or an inability to work, any post about work-related activity can be used against you. This includes posts about freelance projects, volunteer work, or even casual comments about being busy. The safest approach is to avoid work-related content entirely while your claim is open.
Rule 5: Ask friends and family to avoid tagging you. You cannot control what others post, but you can ask them not to tag you in photos or share your location. Explain that you are in the middle of a legal claim and that their posts could affect your case. Most people will understand and respect your request.
Rule 6: Consult an attorney before making any changes. If you are unsure about a specific post or are considering deleting content, talk to an attorney first. Deleting posts can create legal problems, and an attorney can advise you on the safest course of action. They can also help you understand what the insurer may be looking for and how to respond if you are asked to produce social media content.
These rules are not about hiding the truth; they are about preventing the insurance company from taking your words and images out of context. You have the right to live your life and to share it online, but you also have the right to protect your claim from being unfairly undermined. By following these guidelines, you can reduce the risk of your social media activity being used against you.
If you have already posted something that concerns you, do not panic. In many cases, an experienced attorney can help you address the issue before it becomes a major problem. The key is to act early and to avoid making the situation worse by deleting content or posting explanations online. Your attorney can advise you on the best way to handle the situation and protect your interests.
Understanding can insurance company use my social media against my injury claim is the first step toward protecting yourself. The next step is to take action. Review your privacy settings, talk to your friends and family, and consult with an attorney who understands the digital side of personal injury claims. With the right approach, you can keep your online presence from becoming a liability in your case.
Your social media accounts are not private in the way you might think, and the insurance company will use whatever information it can find to reduce your settlement. The good news is that you have control over what you post from this moment forward. By staying informed and being cautious, you can protect your claim and focus on your recovery.