
Bicycle Accident Liability and Compensation Options
Understand bicycle accident liability and compensation options. Call (833)-248-4565 for a free case evaluation and maximize your recovery.
By Giselle Norwood
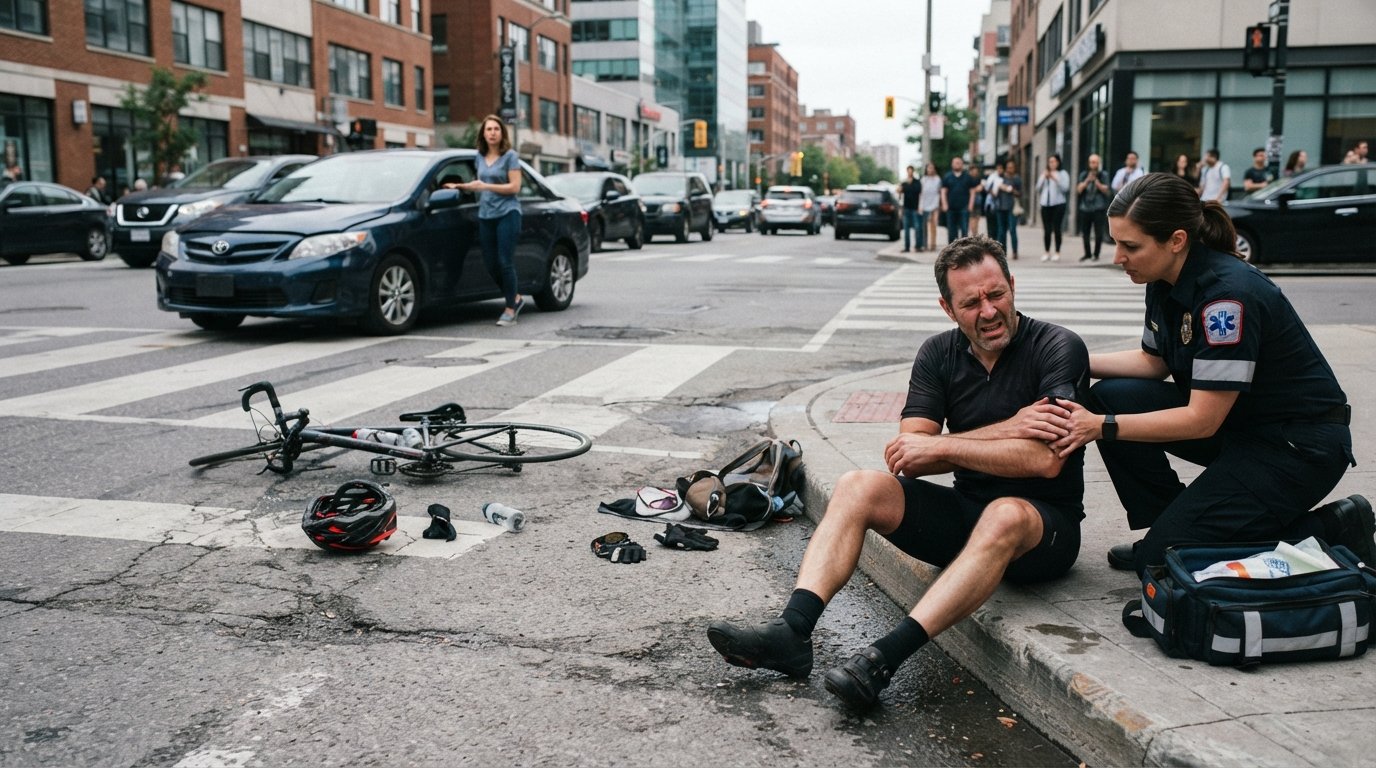
A bicycle accident can happen in a split second, and the aftermath often leaves riders facing medical bills, lost wages, and a confusing tangle of insurance claims. Whether a car door swung open into your path, a driver turned left without seeing you, or a defective bike part failed on a descent, the question of bicycle accident liability and compensation options quickly becomes the center of your recovery. Understanding who is legally responsible and what damages you can pursue helps you avoid accepting a lowball settlement or missing a critical deadline. The sections below walk through fault rules, insurance tactics, evidence you need, and the realistic paths to compensation so you can make informed decisions with confidence.
Who Is Liable After a Bicycle Accident?
Liability in a bicycle accident usually rests on negligence: someone failed to act with reasonable care, and that failure caused your injuries. In most collisions with motor vehicles, the driver is the primary defendant, but liability can spread across multiple parties. A city may be responsible for a pothole or broken traffic signal. A manufacturer may be liable for a faulty brake or helmet. Even another cyclist or a pedestrian can share fault. The key is proving that a specific party owed you a duty of care, breached that duty, and directly caused your harm.
Comparative negligence rules vary by state and heavily influence your recovery. In a pure comparative negligence state, you can recover damages even if you were 90 percent at fault, though your award is reduced by your percentage of fault. In a modified comparative negligence state, you recover nothing if you are found 51 percent or more at fault (or 50 percent in some states). A handful of contributory negligence states bar recovery entirely if you share any fault. This is why a driver's insurer will often try to pin partial blame on you, claiming you ran a red light, wore dark clothing, or swerved unpredictably. Documenting the scene and preserving evidence early is essential to counter those arguments.
Common liable parties in bicycle accident claims include:
- Motor vehicle drivers who were distracted, speeding, impaired, or failed to yield
- Government entities responsible for road maintenance, signage, or dangerous design
- Bicycle or component manufacturers when a defect caused the crash
- Property owners whose dogs, obstacles, or unsafe conditions contributed to the incident
- Employers whose drivers were on the job at the time of the collision
Identifying all potential defendants matters because each may carry different insurance limits and assets. A single driver with minimum coverage might not cover your losses, but an employer's commercial policy or a manufacturer's product liability coverage could provide additional recovery. An experienced attorney can investigate these layers and pursue every applicable source.
Insurance Coverage and How Claims Are Handled
After a bicycle accident, you will likely deal with several insurance policies. The driver's bodily injury liability coverage is the first target, but it may be insufficient. Your own auto insurance uninsured/underinsured motorist (UM/UIM) coverage can step in if the at-fault driver has no insurance or too little to cover your damages. Many cyclists do not realize their auto policy's UM/UIM benefits may extend to them while riding a bike, even if no car was involved in the crash. Medical payments coverage (MedPay) on an auto policy or health insurance can also pay accident-related medical bills regardless of fault.
Insurance adjusters are trained to minimize payouts. They may call you shortly after the crash, ask for a recorded statement, or request blanket access to your medical records. These tactics are designed to lock you into a version of events or uncover pre-existing conditions they can use to reduce your claim. Politely decline recorded statements until you have spoken with a lawyer, and never sign a release or accept a quick settlement before you understand the full extent of your injuries. Soft tissue injuries and concussions can take weeks to fully manifest, and an early settlement forecloses any future claim.
If you are unsure how to start the claims process, a step-by-step guide on filing a claim after a bicycle accident can help you organize evidence, notify insurers, and protect your rights from the first phone call. The more organized you are early on, the stronger your negotiating position becomes. Keep a dedicated folder for police reports, witness contact information, medical records, repair estimates, and a pain journal that tracks your recovery day by day.
When liability is disputed or the insurer refuses to negotiate fairly, litigation may become necessary. Filing a lawsuit does not automatically mean a trial; most cases settle after discovery. But having a lawyer who is prepared to litigate often changes how insurers value your claim. They know an unprepared claimant may fold, while a well-represented one can push the case to a jury.
Compensation Options: What You Can Recover
Compensation in a bicycle accident case falls into two broad categories: economic damages and non-economic damages. Economic damages are the measurable financial losses: medical bills, future medical care, lost wages, lost earning capacity, bike repair or replacement, and out-of-pocket expenses like rideshare fares to appointments. Non-economic damages cover the intangible harm: pain, suffering, emotional distress, loss of enjoyment of life, and in some cases loss of consortium for a spouse. A few states also allow punitive damages when the at-fault party's conduct was especially reckless, such as drunk driving.
Calculating a fair number requires more than adding up receipts. Insurers often use a multiplier method or a per diem approach to estimate pain and suffering, but those formulas can undervalue serious injuries. A more reliable approach is to document how the injury has changed your daily life. If you can no longer commute by bike, play with your children, or sleep through the night, those losses have value. A life care planner or medical economist can project future costs for catastrophic injuries like spinal cord damage or traumatic brain injury.
Your compensation options also depend on the insurance policies available and the assets of the at-fault party. Common sources include:
- The driver's bodily injury liability policy
- Your own uninsured/underinsured motorist coverage
- MedPay or health insurance for immediate medical bills
- Commercial policies if the driver was working at the time
- Product liability claims against manufacturers or sellers
- Government tort claims for dangerous road conditions
Each source has its own rules, deadlines, and documentation requirements. Government claims, for example, often require a formal notice within 60 to 180 days, far shorter than the standard statute of limitations. Missing that window can destroy an otherwise valid claim. An attorney can map out every available policy and ensure no deadline is overlooked.
Evidence That Strengthens Your Claim
Strong evidence is the backbone of any bicycle accident claim. The moments right after a crash are chaotic, but what you do in the following hours and days can determine whether you receive fair compensation. Call 911 immediately so a police report is created. Exchange information with the driver, but do not argue about fault. Take photos of your injuries, the bike, the vehicle, the road conditions, and any visible skid marks or debris. Collect names and contact information from witnesses before they leave the scene.
Preserve your bicycle and gear in the condition they were in after the crash. Do not repair or discard them until your lawyer or an investigator has had a chance to inspect them. If a defective component played a role, that physical evidence may be crucial. Seek medical attention even if you feel fine; adrenaline can mask pain, and a delay in treatment gives insurers ammunition to argue your injuries were not serious or were caused by something else. Follow your doctor's advice and keep every appointment.
Digital evidence can also be powerful. Many cyclists ride with action cameras or use fitness apps that record speed, route, and time. Surveillance cameras on nearby businesses or homes may have captured the collision. A skilled attorney can send preservation letters to prevent that footage from being overwritten. Similarly, event data recorders in newer vehicles can show speed, braking, and steering inputs in the seconds before impact. Gathering this evidence quickly is essential because it can disappear within days.
Finally, keep a detailed journal. Write down what you remember about the crash, how your injuries affect you each day, and any conversations with insurance adjusters. Memory fades, and a contemporaneous record is far more persuasive than a vague recollection months later. This journal can also help your doctor understand the full impact of your injuries and support your claim for pain and suffering.
The Role of a Lawyer and Free Case Evaluations
Hiring a lawyer does not have to be expensive upfront. Most personal injury attorneys work on a contingency fee basis, meaning you pay nothing unless they recover compensation for you. This aligns their interests with yours and removes the financial barrier that keeps many injured cyclists from seeking help. During a free case evaluation, an attorney will review the facts, explain the applicable liability rules, and give you an honest assessment of your options. There is no obligation to hire, and the conversation is confidential.
An attorney can handle negotiations with insurers, gather and preserve evidence, consult with accident reconstruction experts, and file a lawsuit if necessary. They also understand the tactics adjusters use and can counter lowball offers with documented damages and legal precedent. If your case involves a product defect or a government entity, the legal complexity increases, and having counsel becomes even more important. Platforms like LawyerOffer connect injured people with qualified attorneys who can evaluate their claims and explain the compensation options available. These services are designed to make legal help accessible, especially for those who are unsure where to turn after a serious injury.
Before you speak with an attorney, gather your documents: police report, medical records, photos, witness statements, and any correspondence from insurers. Write down your questions so you do not forget them. Ask about the attorney's experience with bicycle accident cases, their fee structure, and how they communicate with clients. A good fit is someone who listens, explains things clearly, and responds promptly. Do not feel pressured to sign with the first lawyer you speak with; a free consultation is an opportunity to interview them as much as they are evaluating your case.
Steps to Take After a Bicycle Accident
Knowing what to do in the immediate aftermath can protect your health and your claim. The following steps provide a practical framework:
- Call 911 and request police and medical assistance. A formal report creates an official record of the crash.
- Exchange information with the driver, including name, insurance, license plate, and contact details. Do not discuss fault.
- Document the scene with photos and videos. Capture the position of vehicles, road conditions, traffic signals, and your injuries.
- Collect witness names and phone numbers. Independent witnesses can be invaluable if liability is disputed.
- Seek medical attention promptly and follow all treatment recommendations.
- Preserve your bicycle and gear. Do not repair or discard anything until advised.
- Notify your own auto insurer if you have UM/UIM or MedPay coverage, even if the other driver was at fault.
- Keep a detailed file of all bills, lost wage documentation, and a pain journal.
- Consult a personal injury attorney before giving a recorded statement or accepting any settlement.
Following these steps does not guarantee a specific outcome, but it dramatically improves your chances of a fair recovery. Insurers build their defenses around gaps in evidence and inconsistent statements. A well-documented claim leaves little room for them to argue that your injuries were minor or that you were partly to blame. If you are unsure about any step, err on the side of caution and seek professional guidance early.
Common Mistakes That Reduce Compensation
Even well-intentioned cyclists make mistakes that undermine their claims. One of the most common is delaying medical treatment. Insurers interpret gaps in care as evidence that you were not seriously hurt. Another is apologizing at the scene, which can be construed as an admission of fault. Do not say "I'm sorry" or "I didn't see you" even if you feel embarrassed or shaken. Stick to the facts and let the investigation determine fault.
Posting about the accident on social media is another trap. Defense attorneys and adjusters routinely review public profiles for photos or comments that contradict claims of injury. A picture of you hiking or dancing months after the crash can be taken out of context and used to devalue your pain and suffering. Adjust your privacy settings and avoid discussing the case online. Similarly, do not sign medical authorizations that give insurers unlimited access to your entire medical history. They only need records related to the accident, and broad authorizations can expose unrelated conditions they may use against you.
Finally, do not accept a settlement before you know the full extent of your injuries. Once you sign a release, you cannot go back for more money even if you need surgery later. A seemingly generous offer may barely cover your current bills and leave nothing for future care. An attorney can help you evaluate whether a settlement is truly fair or whether it is a lowball attempt to close the file cheaply. If you are uncertain, get a second opinion before signing anything.
Statutes of Limitations and Deadlines
Every state sets a statute of limitations for personal injury claims, typically ranging from one to three years from the date of the accident. Miss that deadline and you lose the right to sue, no matter how strong your case. Government claims have even shorter notice requirements, sometimes as little as 60 days. Product liability claims may have their own rules, and if the victim is a minor, different tolling provisions may apply. Because these deadlines are strict and vary by jurisdiction, it is critical to consult an attorney as soon as possible after a bicycle accident.
Even if you are negotiating with an insurer, do not assume the statute of limitations is paused. Settlement talks do not toll the deadline unless both parties agree in writing. If negotiations stall near the deadline, your attorney may need to file a lawsuit to preserve your rights. Filing does not mean the case will go to trial; it simply keeps your options open while the parties continue to negotiate. Waiting until the last minute limits your choices and gives the other side more leverage.
Bicycle accident liability and compensation options are rarely simple, but you do not have to navigate them alone. From identifying every liable party to calculating future medical costs and countering insurance tactics, the process rewards preparation and informed decision-making. Whether you pursue a claim on your own or with legal help, acting quickly to preserve evidence and understand your rights is the most reliable way to protect your recovery.